Subordinated loans
The standard: fixed-interest loan with qualified subordination – clearly calculable, without profit sharing. Details: Subordinated loans.

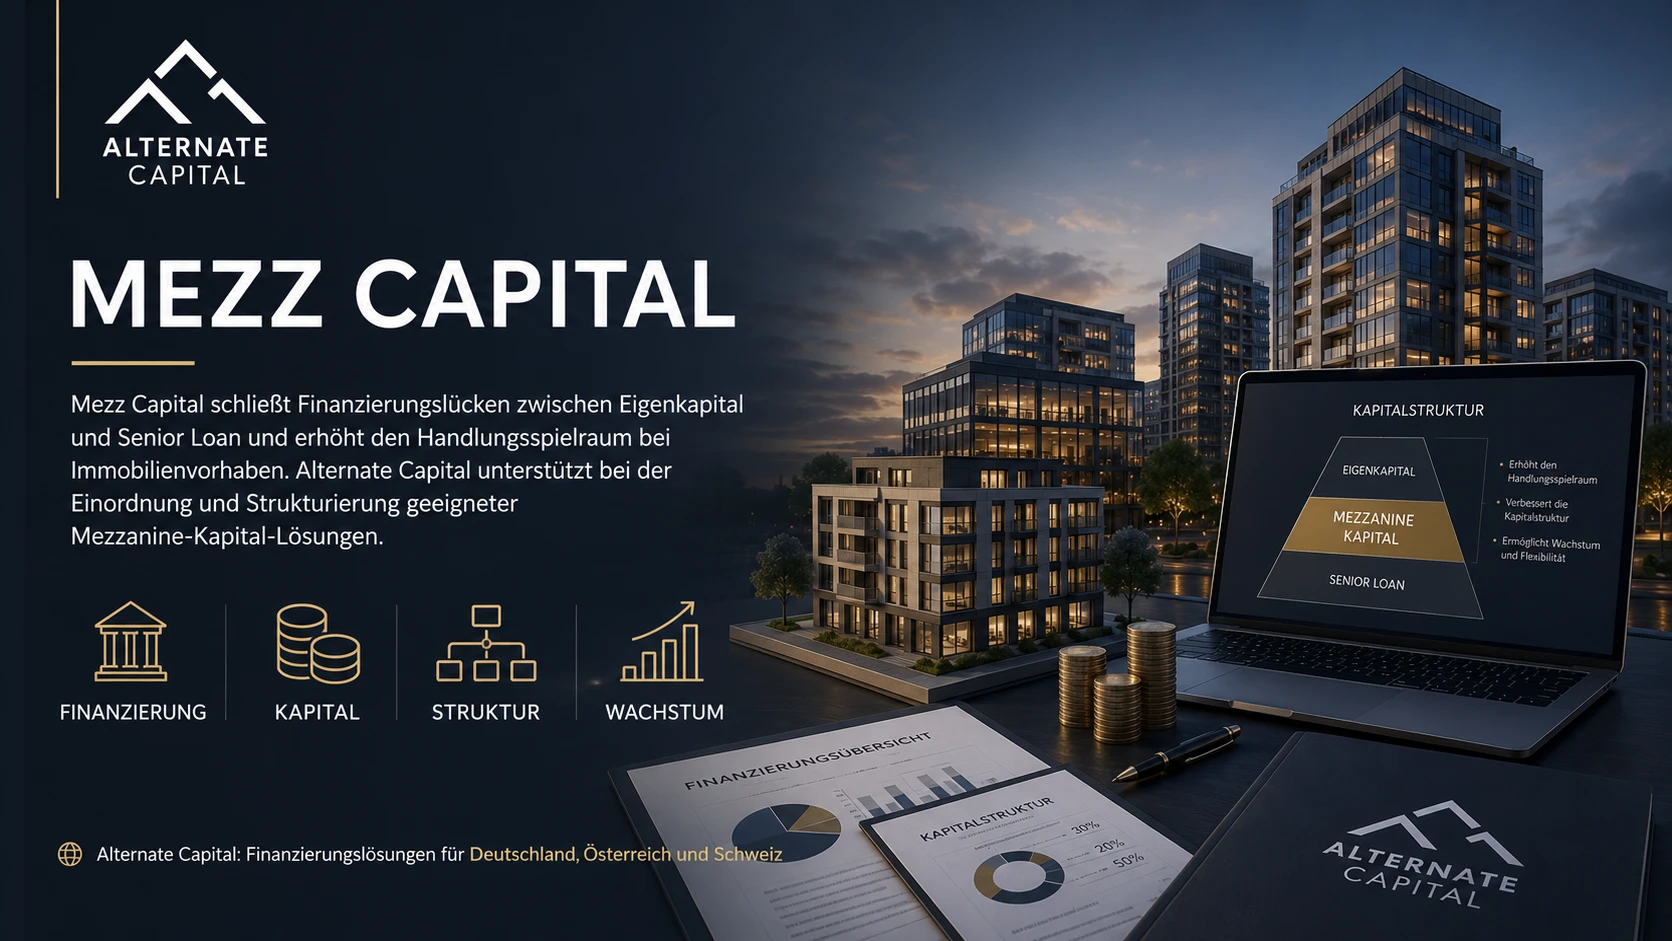
Alternate Capital is the real estate finance division of Alternate Immobilien GmbH – and mezzanine capital is its core instrument: subordinated capital, which closes the gap between the bank and equity. This page bundles why this capital makes sense for real estate projects, what forms there are and what the current market situation looks like.
The importance of mezzanine capital in real estate finance has grown since the turnaround of interest rates, not shrunk: banks finance more conservatively – leverage of 65–75 % instead of 80–90 % are the new standard. The difference has to come from somewhere, and pure equity is the most expensive and scarce raw material in today’s project sizes.
mezzanine capital solves exactly this problem: It replaces part of own funds, can be treated economically like equity by the bank because of its subordinated ranking, while allowing the project sponsor to retain control: no shares, voting rights or dilution. The cost is an interest rate well above bank lending rates. The structure makes economic sense where the project margin and benefit of equity leverage outweigh the additional costs.
At Alternate Capital, mezzanine is therefore not a niche product, but a core component of almost every larger structure – in conjunction with Senior loans, Whole loans and Bridge finance.
The standard: fixed-interest loan with qualified subordination – clearly calculable, without profit sharing. Details: Subordinated loans.
Fixed basic interest rate plus participation in the project profit – reduces the ongoing burden, costs in case of success.
The capital provider participates in the project company without appearing externally as a partner. Depending on the structure, the investment can have equity-like balance sheet characteristics.
Securitized remuneration entitlements without shareholder creation – flexible, but documentation-intensive; rather for larger issues.
Every basic form can be combined with a success component – the mixture of fixed interest and kicker is a matter of negotiation.
Bank loan agreements, balance sheet objectives and the exit strategy determine the choice. We structure the option that fits the project and overall financing. Further reading: Equity capital and interest rates.
The turnaround in interest rates has also sorted the subordinate world: some lenders have withdrawn after project failures, the remaining Test harder and draw more selectively. Increased basic interest rates also raise yield expectations – anyone looking for mezzanine today competes for less capital at higher requirements.
In concrete terms, this means that projects without real own funds, without a track record or without a resilient exit fail early. Opportunities have projects with substance – conservatively calculated, cleanly documented, by experienced sponsors. And this is where our role lies: we know the addresses that are currently financing, know what their committees want to see, and bring your request into the form that carries through the audit.
To be honest, We, too, cannot make weak projects financially viable – but we prevent good projects from failing due to poor preparation. This is the key difference in the current market.
Bridge and mezzanine are siblings with different jobs: The Bridge finance Determined Time problems First-ranking, short-range, fast. Mezzanine solves the problem Equity problems – subordinated, equity-substituting. In practice, both often work together: the bridge secures the purchase under time pressure, mezzanine then leverages the project phase; or subordinated capital bridges itself – for example until sales proceeds flow.
The total invoice of costs, term and exit decides which combination bears – which is exactly what we set up before you commit. For integrated solutions from a single source, it is also worth taking a look at Whole loans.
mezzanine capital does not only work in the new building: About the Additional borrowing activate property investors free lending reserve – as a subordinate tranche in the second rank, without touching the existing bank. The released capital serves as a replacement for own funds in the next project, for Capex programs or purchases.
For the classification of industry inquiries: Mezzanine also exists in the corporate financing of other industries – but the focus of Alternate Capital is clearly on Real estate projects in the Germany, Austria and Switzerland. There we know lenders, valuation logic and pitfalls; trips to foreign asset classes would be dubious.
No – we structure and mediate: The capital comes from debt funds, family offices and institutional addresses from our network. Our independence keeps the competition for your financing open.
From about €750,000 subordinated demand, up to double-digit million amounts – in Germany, Austria and Switzerland.
Success-related, agreed in advance transparently; the initial estimate is free of charge. There is no prepayment for “exams”.
With the basic data about the Initial assessmentProject, costs, own funds, exit – response usually within 1–2 working days.
mezzanine capital rarely unfolds its value alone, but in conjunction with the other capital strata. At Alternate Capital, we therefore always think of real estate finance as a whole: The first-ranking senior loan forms the favorable foundation, the mezzanine capital closes the equity gap, and a bridge finance bridges time-critical phases if necessary. Only this overall view makes individual building blocks a viable structure.
The advantage of structuring all building blocks from a single source lies in the coordination. Subordination, intercreditor agreement and payout order between bank and mezzanine lenders have to fit together – if something goes wrong here, in the worst case, the entire financing bursts shortly before the conclusion. Because we coordinate both sides, this most common cause of failed deals is eliminated.
Thus, mezzanine capital is not mediated as an isolated product at Alternate Capital, but as an integral part of a well-thought-out capital structure. The result is financing that fits the project phase, the exit and the risk-bearing capacity – and that uses the equity leverage without overburdening the project.
Submit the key data of your project – we check feasibility, define the structure and address the lenders that is currently financing.

Jürgen Kronawitter specialises in structured real estate finance. He helps property investors, developers and portfolio owners implement complex financing solutions. His work focuses on structuring and arranging senior loans, whole loans, mezzanine capital and bridge loans, as well as tailored financing for acquisitions, investment properties, developments and refinancing. By combining conventional bank lending with alternative capital sources, he develops financing structures for domestic and international property projects.
Jürgen Kronawitter on LinkedIn → More about the author