Increase the loan with the existing bank
The existing lender increases its first-ranking loan. This can be straightforward if the bank agrees and the terms remain competitive.

Principal repayments and increased property values can create unused borrowing capacity. Additional borrowing can turn that capacity into liquidity for acquisitions, refurbishment or another project’s equity contribution. Alternate Capital structures facilities from €750,000 in Germany, Austria and Switzerland.
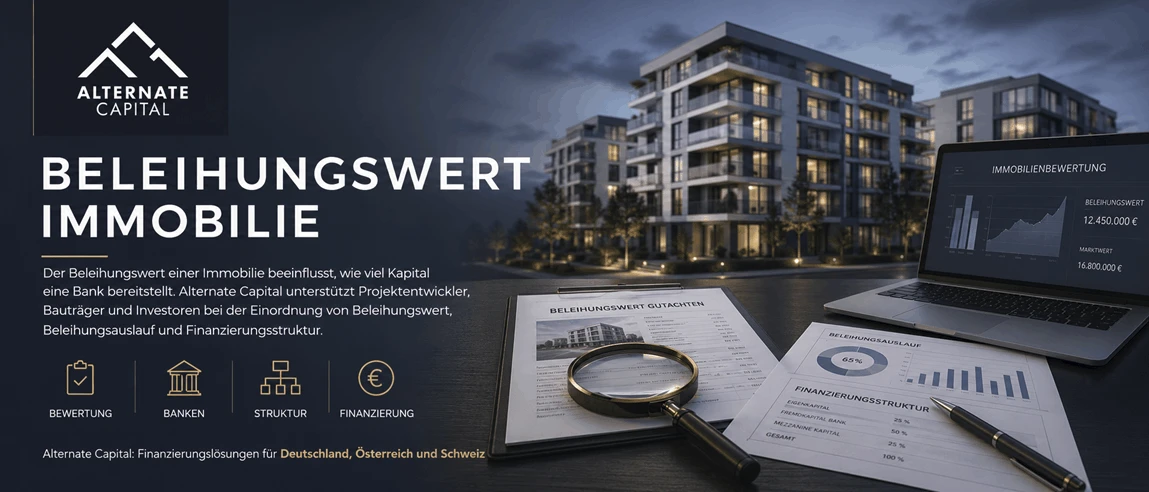
The starting point is the difference between the current Mortgage lending value of your property and the existing secured debt: its available borrowing capacity. Where sufficient capacity exists, options include increasing the existing loan, arranging subordinated debt or undertaking a full Refinancing.
For example, an apartment building bought for €4.5 million is now worth €6.5 million, with €2.4 million outstanding. At 65% LTV, a loan of approximately €4.2 million could release around €1.8 million of liquidity while the property continues to generate rent and remains in the portfolio.
This is why investors consider additional borrowing within portfolio management: it can release equity while retaining the property and avoiding a sale.
The existing lender increases its first-ranking loan. This can be straightforward if the bank agrees and the terms remain competitive.
A second lender lends behind the bank without replacing the existing facility. This can be discreet and relatively quick, with pricing closer to Mezzanine pricing.
A new lender provides a replacement facility, repaying the existing balance and releasing further capacity. This can be particularly relevant when a fixed-rate period ends.
If you plan further acquisitions with the released funds, assess the additional debt service alongside reserves for the existing portfolio. Further reading: Expand your property portfolio with suitable finance.
Equity for the next investment without selling existing properties: an established approach to portfolio growth.
Capital expenditure, energy improvements and repositioning: using available equity to support further property investment.
Available borrowing capacity as a source of own funds for development or project finance, potentially at a lower cost than mezzanine alone.
Distributions, share acquisitions and inheritance settlements: liquidity can support a solution without a forced property sale.
Retain funds to pursue market opportunities when they arise.
Replace overdrafts or interim facilities with lower-cost property-secured finance.
How portfolio owners release equity: structures, requirements and common mistakes.
Original recording in German.
Another episode, “How property professionals use additional borrowing”, is available in the Podcast hub
Original recording in German.
Option 2, a second-ranking facility, may be possible within three to six weeks with complete documents. Increasing a bank loan or refinancing commonly follows a six-to-twelve-week bank process.
The existing bank decides whether to increase its own loan. For a second-ranking facility, review the existing agreement and security arrangements. Clear communication remains advisable, and we can coordinate it.
Rented residential and commercial assets with stable cash flow and sound locations. Stronger occupancy and condition can support higher acceptable leverage.
Borrowing itself does not trigger a tax on the loan amount. Interest deductibility depends on how the funds are used. Your tax adviser confirms the treatment; we provide the financing structure.
An owner seeking liquidity can consider selling or borrowing against the property. A sale produces proceeds without ongoing debt service, while additional borrowing retains the asset. The appropriate choice requires a full comparison.
Selling involves transaction costs and may have tax consequences. It also transfers future rent and capital growth to the buyer. Additional borrowing retains ownership, creates financing costs and allows the released funds to be reinvested. Tax treatment depends on the circumstances.
As a simplified example, a property worth €2 million rising by 3% annually gains approximately €60,000 in value per year. A sale would give up that future exposure and may involve costs exceeding €100,000. Compare these assumptions with borrowing costs before deciding. Neither capital growth nor the outcome is guaranteed.
A sale can be appropriate if an asset no longer fits the strategy, requires substantial refurbishment or has a weaker outlook. For sound income-producing assets, additional borrowing offers an alternative that preserves ownership. We compare both scenarios for the individual property.
Send the property value, outstanding loan and rental income. We will assess realistic borrowing capacity and a suitable structure.

Jürgen Kronawitter specialises in structured real estate finance. He helps property investors, developers and portfolio owners implement complex financing solutions. His work focuses on structuring and arranging senior loans, whole loans, mezzanine capital and bridge loans, as well as tailored financing for acquisitions, investment properties, developments and refinancing. By combining conventional bank lending with alternative capital sources, he develops financing structures for domestic and international property projects.
Jürgen Kronawitter on LinkedIn → More about the author