Debt funds
Specialised loan funds with clear lending criterias: fast examination, professional documentation, tickets from 2 to 50+ € million – the standard partner for larger subordinate tranches.

Mezzanine lenders closes the gap that banks leave open: Debt funds, family offices and institutional addresses subordinate, which is no longer possible. This page shows who these lenders are, what they are checking – and how the targeted address via Alternate Capital works.
Mezzanine lenders Subordinated capital ready – the layer between first-ranking bank loan and equity. They accept the subordination behind the bank and are paid for it with significantly higher interest rates than first-rank lenders. Legally, it usually goes through Subordinated loans, partly secured by subordinated land charge or share pledging.
The key difference to the bank lies in the business model: banks refinance cheaply and have to remain regulatoryly conservative; mezzanine lenders invest investor capital with yield targets in the high single-digit to double-digit range – and can draw risks that do not fit into any bank grid. For project sponsors, this means Flexibility and growth: more project volume with the same own resources, faster decisions, more individual structures.
Specialised loan funds with clear lending criterias: fast examination, professional documentation, tickets from 2 to 50+ € million – the standard partner for larger subordinate tranches.
Asset managers of individual families: flexible in structure and duration, relationship-driven, partly with real estate expertise – ideal for special situations and medium-sized tickets.
Institutional investors with a long horizon: more conservative profiles, but reliable processes – relevant for large-volume, well-secured structures.
Entrepreneurs and wealthy private individuals, often bundled: fast and pragmatic with smaller tranches – quality of documentation and support varies.
Digitally collected subordinated capital for smaller projects: standardized and public – usually unsuitable for discreet, larger projects.
Region, asset class, phase, ticket and risk appetite must fit the project – selecting the right five addresses is more important than a list of fifty.
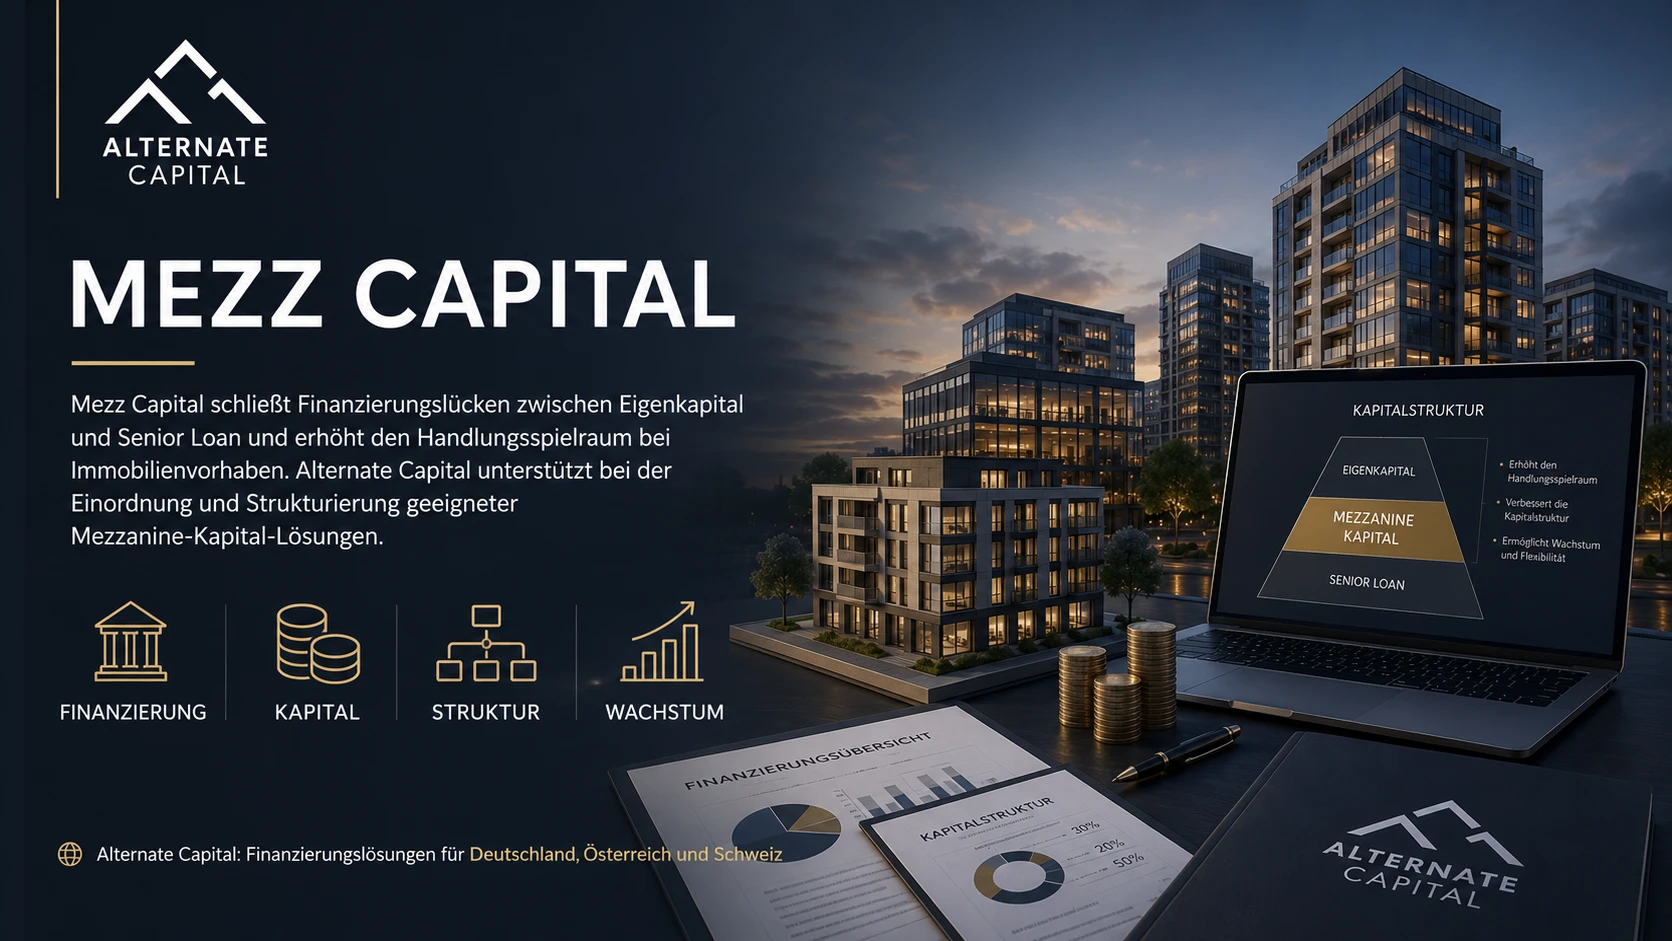
Real estate projects tie up a lot of capital in clearly defined periods with real collateralized assets – exactly the profile that subordinated capital needs: The lenders can take risk via land register and project review, the project sponsors leverages his own funds without surrendering shares.
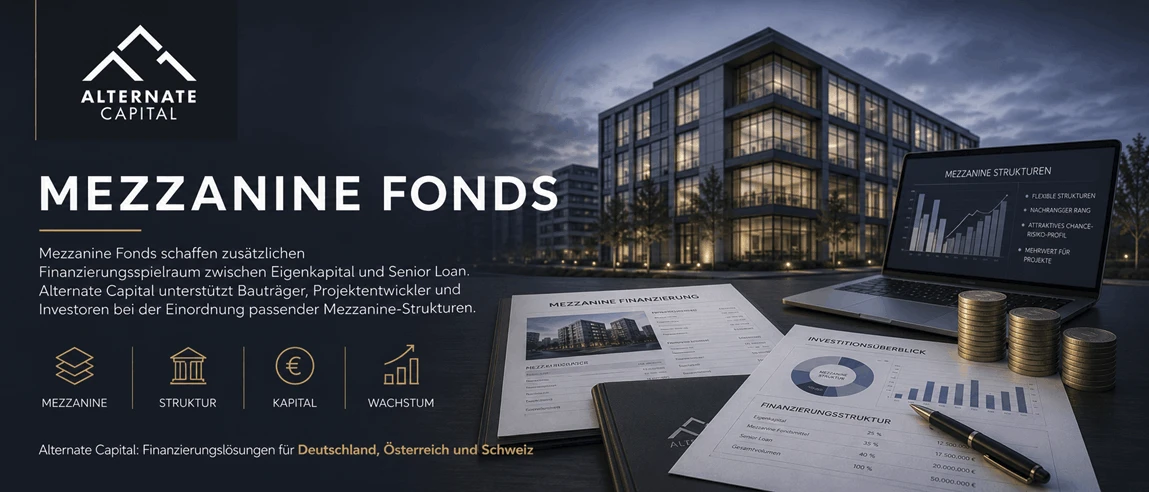
Typical constellation: The bank finances 65–75 % of the costs, the mezzanine lenders 10–25 %, real own funds remain 5–15 % in real terms. The result: more projects in parallel, higher return on equity, control received – against interest costs, which are usually moderate in the mixed calculation. The complete cost consideration is provided by the guide Mezzanine interest rates.
For property developers and property developers Mezzanine financing is the classic growth lever – the calculation example shows the page mezzanine capital for property developers.
Project, own funds, senior structure, exit – we check whether and to what extent subordination can be displayed.
Exposé, figures, sensitivities, collateral concept – prepared as investment committees decide.
Shortlist of matching mezzanines lenders from the network, discrete parallel address, structured comparison of the term sheets.
Coordinate conditions, subordination and intercreditor with the bank – until payment and beyond.
How lenders think, what they check and how the address succeeds – from the mediation practice.
Original recording in German.
All episodes in the Podcast hub
Original recording in German.
Basically yes – direct contacts often fail due to a lack of fit and document quality. lenders efficiently only check what falls into their profile and is prepared in a committee-ready manner; that is exactly what we ensure.
Three to six suitable addresses in parallel – enough for competition, little enough for discretion. Mass mail “burns” projects in the market.
Our remuneration is performance-related and is transparently agreed before the start of the mandate; the initial estimate is free of charge.
Yes, mezzanine also exists in corporate financing. Our network and this page focus on real estate projects in the Germany, Austria and Switzerland from €750,000 subordination requirements.
Mezzanine lenders make their decisions in investment committees – and these committees look for a clear grid. Whoever delivers the documents that this grid expects, gets quick promises; whoever leaves gaps, produces queries and delays. From hundreds of financing processes, we know what matters.
The focus is on the financial model: a comprehensible calculation of the total costs, the expected revenues and – crucially – the sensitivities. What happens if the construction costs increase by 10 %, the sale takes six months longer or the prices 5% are lower? A lender wants to see that its capital also flows back in the stress scenario. In addition, there is the proof of own funds, a robust exit concept, the presentation of the sponsor track record and a clear picture of the collateral structure.
Equally important is coordination with first-ranking financing. The mezzanine lender needs to know how his tranche relates to the senior loan – subordination, intercreditor agreement, payout order. If these points are clarified in advance, the most common cause for ruptured financing is eliminated: the disagreement between the lenders at the last minute. We prepare this entire package in such a way that it follows the logic of the committees and translate your project into their language. The result is shorter assessment times, fewer queries and conditions that reflect the actual quality of your project – not the uncertainty about an incomplete request.
Submit the key data – we will tell you which lenders types fit your project and start the discreet address on request.

Jürgen Kronawitter specialises in structured real estate finance. He helps property investors, developers and portfolio owners implement complex financing solutions. His work focuses on structuring and arranging senior loans, whole loans, mezzanine capital and bridge loans, as well as tailored financing for acquisitions, investment properties, developments and refinancing. By combining conventional bank lending with alternative capital sources, he develops financing structures for domestic and international property projects.
Jürgen Kronawitter on LinkedIn → More about the author