Subordinated to the bank
Qualified subordination behind first-rank creditors – this makes the tranche work for the bank like equity and improves the overall structure.

Equity capital promises project sponsors capital without a bank – at interest rates that at first glance discourage. This page classifies how share capital and mezzanine financing are related, what justifies the high mezzanine capital interest rate and when the capital still pays off.
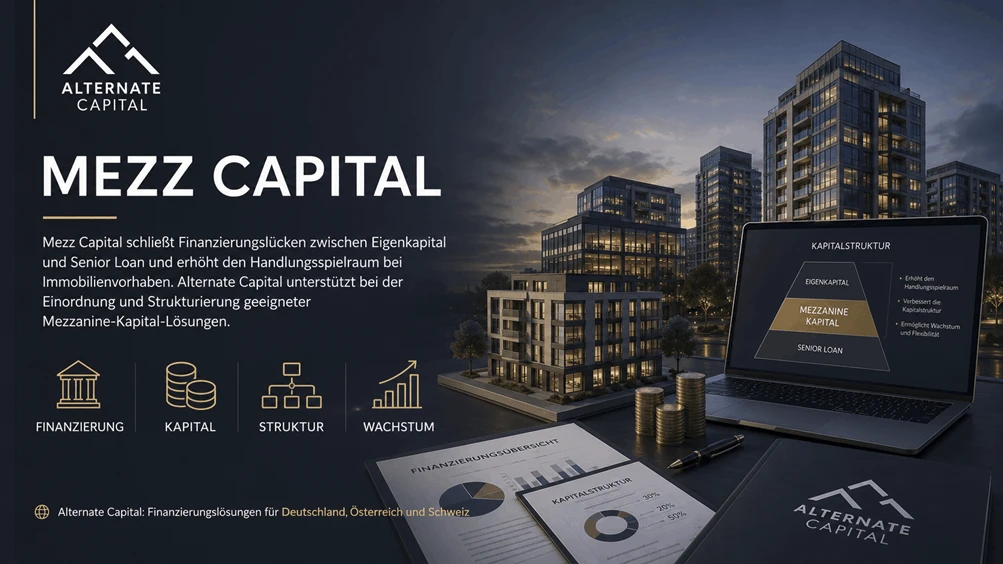
Equity capital is the umbrella term for capital that an investor leaves to a company or project and participates in success – from real shareholder participation (equity) to hybrid forms. Mezzanine financing occupies the middle of this spectrum: economically close to equity, legally mostly debt capital – as Subordinated loans, silent partnership or profit-participating loan with profit component.
For real estate projects, this intermediate form is ideal: the project sponsors receives equity-substituting capital, Without giving up company shares or voting rights; the lender receives a return for its subordinated risk well above bank level – the famous high mezzanine capital interest rate. The more profit-dependent the remuneration (equity kicker, shareholder elements), the closer – and more expensive – the design.
In short: The high interest rate is not a surcharge out of arbitrariness, but the price of the risk between the bank and the owner.
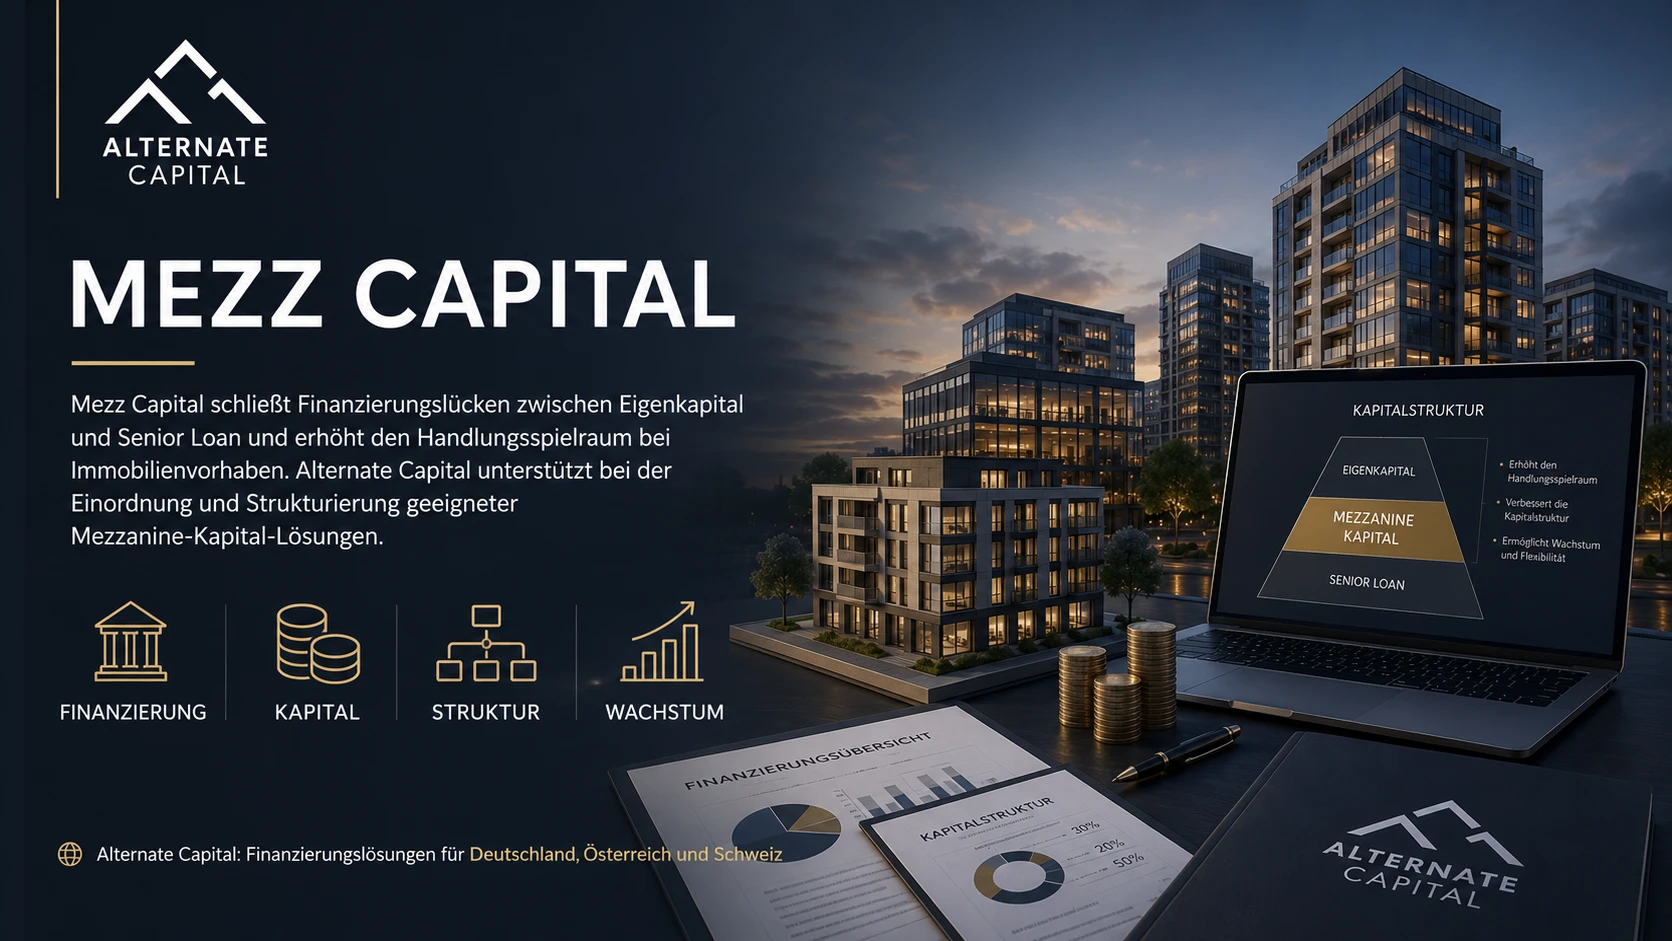
Qualified subordination behind first-rank creditors – this makes the tranche work for the bank like equity and improves the overall structure.
Typical 12–48 months with repayment from sale, refinancing or exit – no ongoing repayment, partially capitalized interest.
Unlike real equity: information and reporting rights yes, participation in the management no.
Fixed interest rate, profit-related components or combinations – the structure determines risk sharing and price.
Subordinated land charge, share pledging, guarantees – each level significantly reduces the interest rate.
Depending on the design, economic equity in the structural consideration – without dilution of the shareholders.
The total costs consist of more than the nominal interest rate: Current interest (market-standard high single-digit to mid-two-digit percentage range p.a.), Capitalised interest rate shares (PIK), Structuring fees (1–3% once) and, if applicable, Equity kicker in the project profit. Offers can only be compared as an effective annual size over the real term.
The risk lies mirror-inverted on the project sponsor: the lever works in both directions. If the project margin shrinks, the debt service eats the profit; if the exit bursts, extension costs or exploitation threaten. Therefore, subordination applies only to projects with a buffer – and only at heights that also bear in the stress scenario. Details and calculation examples: Mezzanine interest rates.
Correctly classifying equity and mezzanine capital interest rate in real estate projects means: knowing the price drivers.
Own funds remain free for further projects · no share or voting levy · improves the banking structure · fast, flexible implementation · leverage on the return on equity · can be designed close to equity in the balance sheet.
Significantly higher costs than bank capital · Repayment pressure at the end of maturity · Reporting obligations · Equity kicker reduces profit in the event of success · leverage has a negative effect on weak projects.
How much capital, how long, for what – and what do the project and exit carry realistically?
subordinated loan, silent partnership or hybrid – matching the bank, balance sheet and risk sharing.
All cost components count on effective annual size – do not compare shop window interest rates.
Does the structure also have a bearing on delay and margin pressure? Only then do they sign.
Subordination, collateral, extension options – with competition from several lenders.
The complete conditional logic for listening – including share capital classification.
Original recording in German.
All episodes in the Podcast hub
Original recording in German.
How equity capital with a high mezzanine capital interest rate still counts, shows a simplified example. A project with a total cost of ten million euros is financed by the bank at 70 percent; two million euros contributes equity as a subordinate tranche, so that only one million euros remains tied to real equity. Even with a double-digit mezzanine capital interest rate, the return on equity remains significantly higher than without the tranche – because the same project profit meets much less used equity.
The decisive factor is the mixed calculation over the entire capital structure. The high interest rate applies only to the subordinated tranche, not to the cheap bank loan. As a result, the weighted total interest rate increases only moderately, while the released own funds make a second project possible in parallel. Anyone who considers the mezzanine capital interest rate in isolation overlooks exactly this leverage effect.
The flip side is honest: the lever works in both directions. If the project profit falls short of the planning, the debt service eats the margin. This is why we expect each structure to be conservative with equity and stress scenarios – only if the mezzanine capital interest rate is also sustainable in the worst case, we structure the tranche.
Submit the key data – we will show you which structure and which interest rate corridor are realistic for your project and address suitable lenders.

Jürgen Kronawitter specialises in structured real estate finance. He helps property investors, developers and portfolio owners implement complex financing solutions. His work focuses on structuring and arranging senior loans, whole loans, mezzanine capital and bridge loans, as well as tailored financing for acquisitions, investment properties, developments and refinancing. By combining conventional bank lending with alternative capital sources, he develops financing structures for domestic and international property projects.
Jürgen Kronawitter on LinkedIn → More about the author