Developing while equity is tied up elsewhere
Your equity is committed to ongoing projects, but the next land acquisition cannot wait. A subordinated facility can bridge the gap and keep your development pipeline moving.

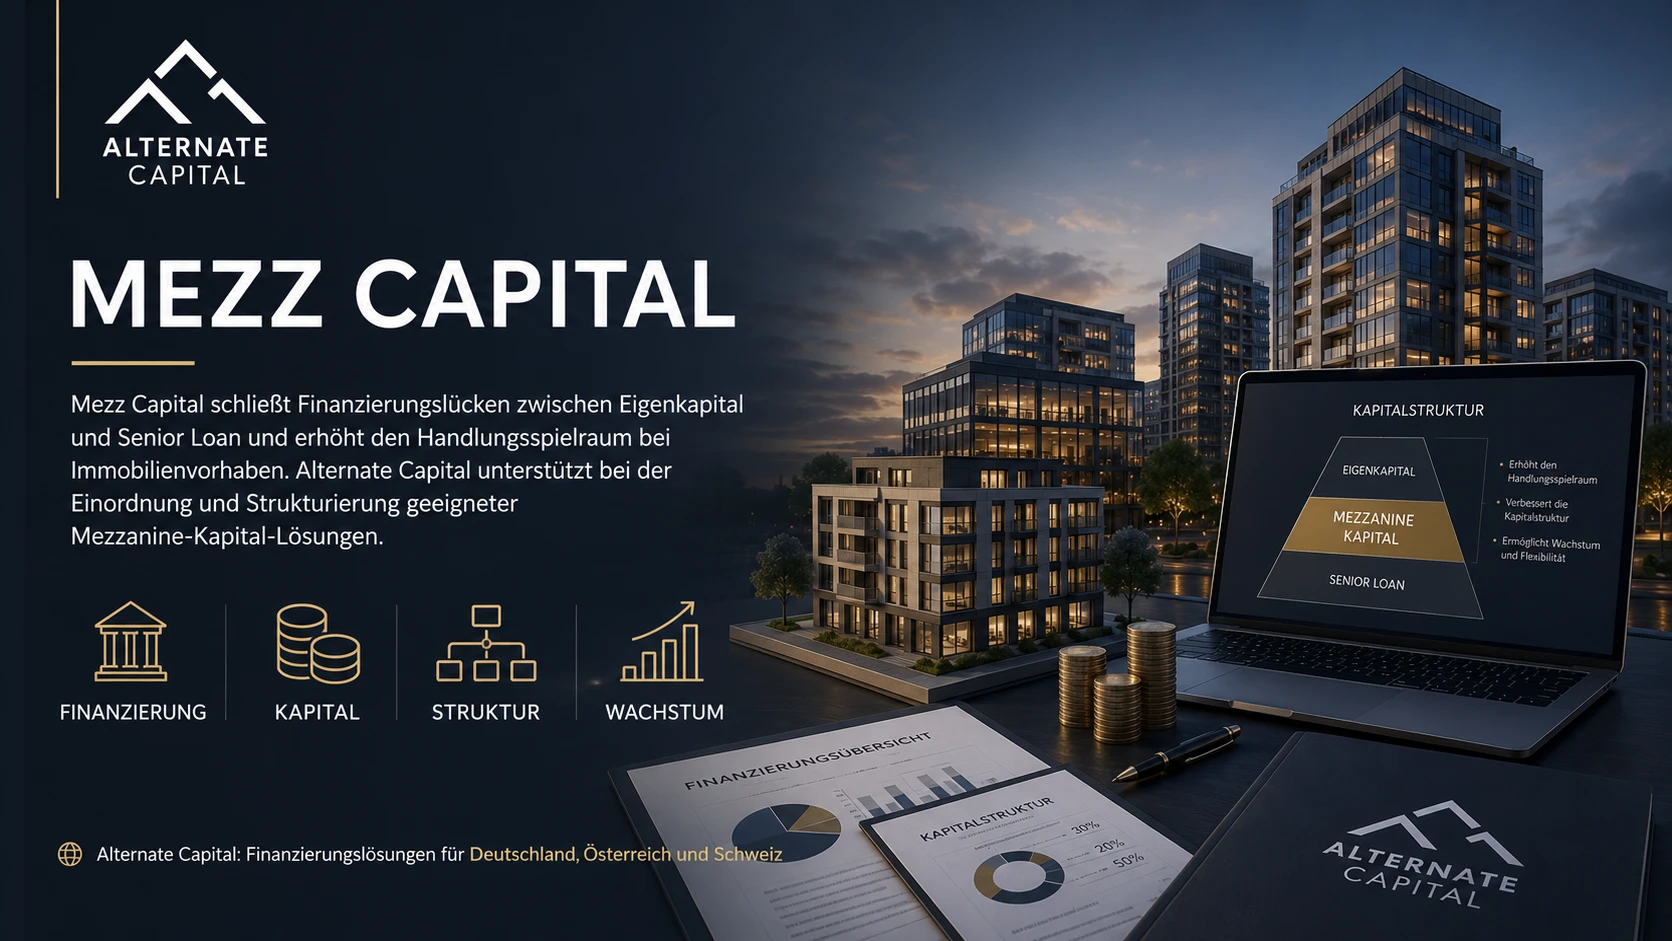
When a senior loan is in place but available equity limits the project size, mezzanine finance can bridge the gap. This subordinated, equity-like capital can fund land acquisition, construction or the release of capital. Alternate Capital structures mezzanine facilities from €750,000 across Germany, Austria and Switzerland.
In architecture, a mezzanine is an intermediate floor. Mezzanine finance occupies a similar position in the capital structure: between the bank’s first-ranking Senior loans and the project sponsor’s equity. It generally takes the form of Subordinated loans with a qualified subordination agreement and, in some cases, a subordinated German land charge.
From the bank’s perspective, the subordinated tranche can serve a similar purpose to additional equity. It improves the financing structure and may make the senior loan possible in the first place. For the project sponsor, this means: more project capacity with the same equity commitment — or the ability to run several projects in parallel rather than one after another.
An indicative structure might comprise bank lending covering 60–75% of total costs, mezzanine capital covering a further 10–25%, and an actual equity contribution of 5–15%. The precise allocation depends on the quality of the project, its location and the lender.
Your equity is committed to ongoing projects, but the next land acquisition cannot wait. A subordinated facility can bridge the gap and keep your development pipeline moving.
Banks are cautious about lending against land without planning permission. Mezzanine capital can bridge the period until permission is granted, before being replaced by project finance.
Combined with Property development finance mezzanine capital can reduce the equity required for each scheme, providing a basis for growth illustrated by our case studies.
Rather than selling assets, portfolio owners can use Additional borrowing secured on a subordinated basis to release liquidity for new investments.
If unit sales are under way but the next project already needs funding, a short-term mezzanine facility can bridge the gap, with repayment from the sale proceeds.
Subordinated capital cannot compensate for a weak project or a complete absence of equity. Lenders require a sound underlying investment and a credible repayment strategy.
Subordination increases the lender’s risk, which is reflected in the price. Mezzanine interest rates are significantly higher than senior loan rates, typically ranging from high single-digit to mid-double-digit annual percentages, depending on leverage, term, project stage and security. Some lenders also charge structuring fees or include a performance-related component, known as an equity kicker.
The key consideration is the blended cost of capital, rather than the mezzanine rate in isolation. Because the subordinated facility accounts for only part of the financing, the increase in the weighted overall interest rate can be moderate, while leverage can materially increase the return on equity. We set out the calculation transparently for your project.
For pricing factors, indicative ranges and worked examples, see our guide to Mezzanine interest rates and our comparison of mezzanine finance and bank loans.
| Feature | Indicative structure |
|---|---|
| Facility amount | From €750,000 to approximately €25 million |
| Term | 12–48 months, depending on the project |
| Ranking | Subordinated to the senior loan, with a qualified subordination agreement |
| Security | Subordinated German land charge, share pledges and guarantees |
| Repayment | Repayment at maturity from a sale, refinancing or another exit |
| Drawdown | In a single amount or in stages as construction progresses |
These five factors influence approval and terms well before the interest rate is discussed.
Our role: As a broker connecting you with suitable mezzanine lenders, we prepare your application to address these five questions before they are raised, helping to shorten the assessment process.
Send us the key project details. We assess whether the funding amount, project stage and structure are suited to subordinated capital.
We establish the facility amount, term, security and relationship with the senior loan.
We discreetly approach suitable mezzanine providers within our network, including debt funds, family offices and institutional lenders.
We compare term sheets, coordinate the subordination arrangements and support drawdown after the agreements are signed.
Our main episode on mezzanine property finance covers applications, costs, common mistakes and circumstances in which subordinated capital is unsuitable.
Original recording in German.
All episodes in the Podcast hub
Original recording in German.
It is generally debt in legal terms, structured as a subordinated loan. Economically, subordination to the bank gives it some characteristics of equity. This hybrid position makes it useful in project finance.
With complete documents, initial feedback is often possible within one to two weeks. Drawdown may take four to eight weeks, depending on the scope of the lender’s assessment.
The limit is the project’s ability to support interest payments and repay the facility. We assess the structure conservatively: a smaller, sustainable tranche is preferable to a larger facility that places excessive pressure on the project.
The Bridge loan provides short-term bridging finance, usually on a first-ranking basis. Mezzanine is additional, subordinated capital that reduces the sponsor’s equity requirement. The two can be combined.
Yes, including for Additional borrowing, capital expenditure programmes or bridging the period before refinancing. The property must have sufficient additional borrowing capacity.
Mezzanine finance is often confused with bringing an equity partner into a property project, but the implications for the sponsor differ considerably. An equity partner receives an ownership interest, voting rights and a say in decisions, as well as a share of the increase in value. That participation may continue for the long term and be worth substantially more than the original investment.
Mezzanine finance works differently. It has some economic characteristics of equity because it is subordinated, but remains debt in legal terms. The lender receives a fixed interest rate, potentially supplemented by a performance-related return, without becoming a shareholder or acquiring a permanent say in the business. Once the loan is repaid, the lending relationship ends and subsequent increases in value remain with the sponsor.
This is the strategic appeal: mezzanine finance can strengthen the funding base and support larger or additional projects without giving up control or long-term value creation. For a developer confident in its pipeline, it can cost less overall than bringing in an equity partner, even if the interest rate initially appears high. The relevant comparison is the value retained after the financing costs, rather than the headline rate alone.
Send us the key details of your project, available equity and timetable. We will give you a realistic assessment of whether a subordinated facility is suitable and the amount that may be achievable.

Jürgen Kronawitter specialises in structured real estate finance. He helps property investors, developers and portfolio owners implement complex financing solutions. His work focuses on structuring and arranging senior loans, whole loans, mezzanine capital and bridge loans, as well as tailored financing for acquisitions, investment properties, developments and refinancing. By combining conventional bank lending with alternative capital sources, he develops financing structures for domestic and international property projects.
Jürgen Kronawitter on LinkedIn → More about the author