A time-sensitive acquisition
An off-market opportunity, bidding process or short completion timetable: bridge finance can secure the acquisition while long-term funding is prepared.

A purchase completing in three weeks, a delayed bank drawdown or an approaching exit can create a temporary funding need. Alternate Capital structures bridge finance from €750,000 with a defined repayment strategy.
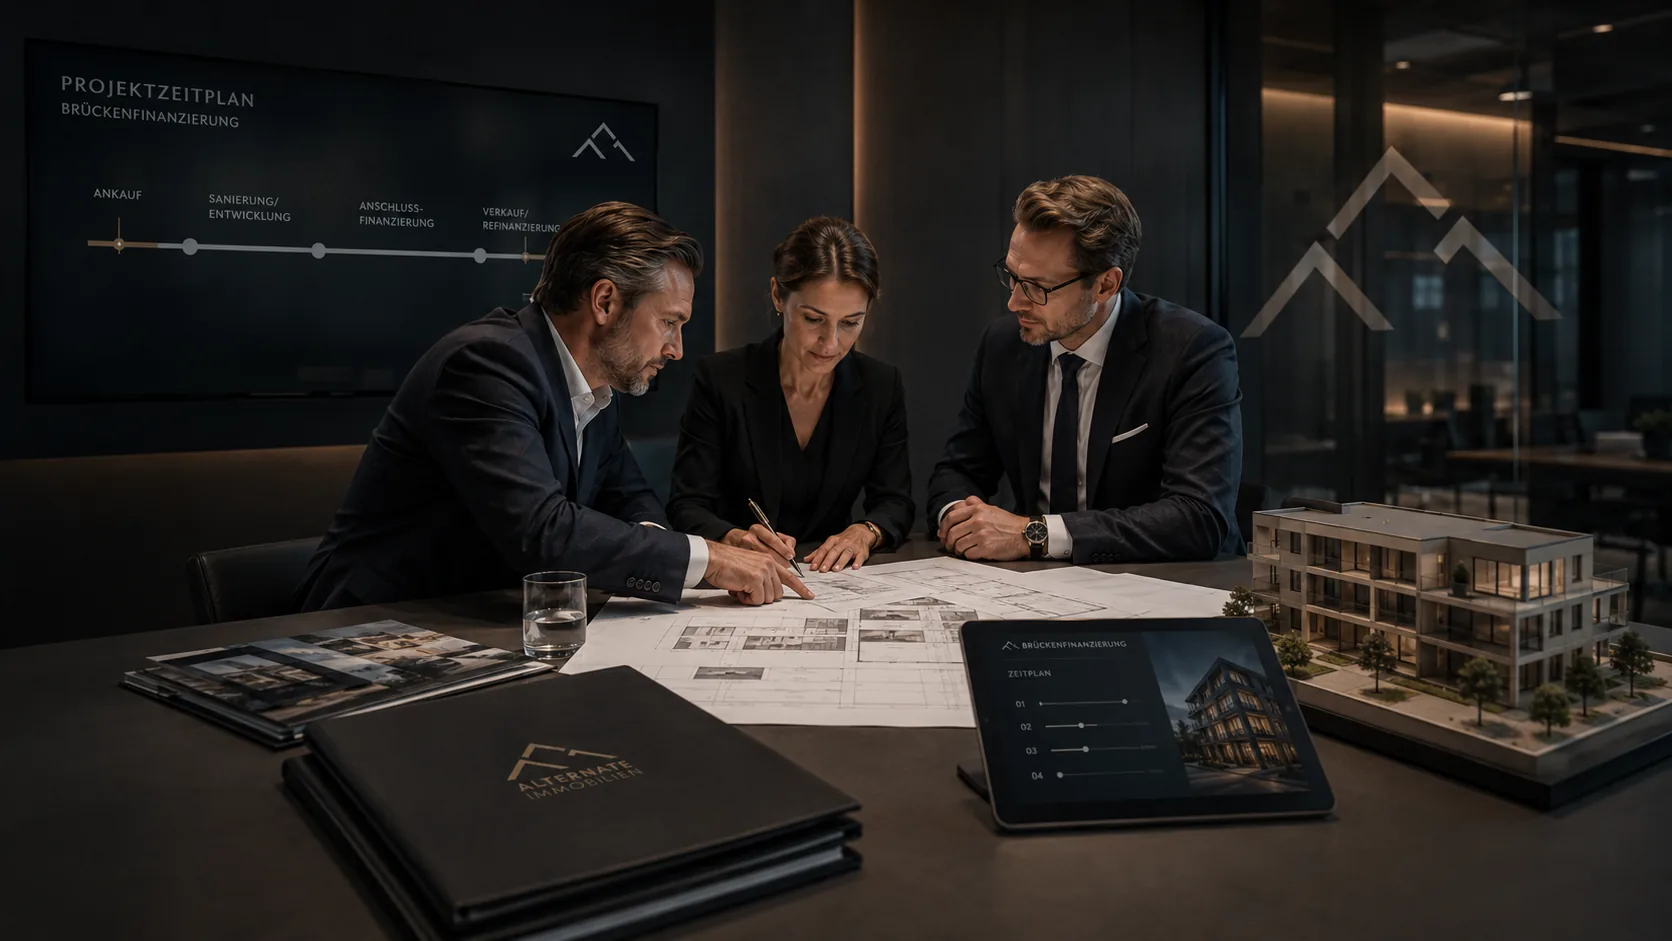
Bridge finance, also known as a Bridge loan , is a short-term property-secured loan. It commonly runs for 6–24 months, with principal repaid at maturity from a defined event such as a sale, long-term loan drawdown or refinancing.
Bridge lenders focus primarily on security and the exit — property value, LTV and a credible repayment plan — rather than lengthy historical cash flow records. This can support faster decisions.
An off-market opportunity, bidding process or short completion timetable: bridge finance can secure the acquisition while long-term funding is prepared.
Where a bank commitment is in place but drawdown conditions take time, interim funding can support the project timetable.
Sales are progressing but another project needs funds now. The facility is repaid from the sale proceeds, with timing and interest assessed carefully.
An expiring fixed-rate period, re-letting or repositioning can require interim finance before long-term refinancing.
Buying promptly, then converting and selling individual units, is an application of Condominium conversion finance.
Bridge funding can provide capacity where conventional processes are too slow, provided the repayment route is credible.
Speed and short duration come at a cost. Indicative annual rates range from high single digits to low double digits, with arrangement or structuring fees. The project-level comparison matters: over six months, one percentage point on €2 million is approximately €10,000, which may be less than the cost of losing an acquisition or missing a deadline.
Compare the complete economics: the acquisition terms, avoided contractual penalties and an earlier project start, alongside finance costs. We also assess a delayed exit before you commit. Further details: Costs of interim finance.
| Feature | Indicative structure |
|---|---|
| Amount | €750,000 – €50 million |
| Term | 6–24 months, with repayment at maturity |
| Security | First-ranking land charge, supplemented where appropriate by assignments |
| Leverage | Approximately 60–75% LTV |
| Interest | Project-specific; interest capitalisation may be available |
| Repayment | Sale, replacement bank loan or refinancing |
Lenders and advisers should assess three exit scenarios:
Sale or refinancing by the target date, with proceeds covering principal, interest and costs with a buffer.
What if the exit is delayed by 3–6 months? Extension options, interest reserves and an alternative such as letting should be assessed.
Assess the downside before you sign: the feasibility of refinancing and holding the property, or a disposal scenario.
Our approach: We do not structure bridge funding where we consider the repayment plan implausible. A credible exit matters to the borrower and the lender relationship.
Applications, costs and repayment planning, explained through financing practice.
Original recording in German.
All episodes in the Podcast hub
Original recording in German.
The terms describe the same broad concept. Our bridge loan page provides further detail for professional property investors: Property bridge loans.
First-ranking security is usual. Subordinated structures may be possible but move closer to Mezzanine capital , with correspondingly higher pricing.
Property documents, including particulars, photographs and an indication of value where available; a land register extract; the purchase agreement or draft; evidence of own funds; and a clear exit strategy. With the Initial assessment lets you start without attaching documents. We will explain what is needed for the next stage.
Often yes, commonly subject to a minimum interest period of three to six months. We consider this clause when an early exit is likely.
A bridge lender’s assessment differs from conventional long-term bank lending. Banks evaluate long-term debt servicing capacity, borrower creditworthiness and letting prospects. A bridge lender concentrates on the quality of the security and the credibility of the exit.
This focus can shorten the process considerably. A bridge lender needs confidence that the property would cover the outstanding loan if necessary and that the repayment plan is realistic. For a valuable property in a suitable location with a clear sale or refinancing strategy, approval may therefore be possible in days rather than months.
For borrowers, this changes the documents that matter. Rather than relying on years of management accounts alone, the lender needs a credible indication of value, a clear land register extract and a plausible exit strategy. We prepare these documents with you to reduce avoidable questions and delays. Preparation can make a substantial difference to the approval timetable.
Property, funding amount, timetable and exit: these four details allow an initial assessment of whether bridge finance is feasible and how quickly it could be arranged.

Jürgen Kronawitter specialises in structured real estate finance. He helps property investors, developers and portfolio owners implement complex financing solutions. His work focuses on structuring and arranging senior loans, whole loans, mezzanine capital and bridge loans, as well as tailored financing for acquisitions, investment properties, developments and refinancing. By combining conventional bank lending with alternative capital sources, he develops financing structures for domestic and international property projects.
Jürgen Kronawitter on LinkedIn → More about the author