
Berlin Mezzanine Finance: An Anonymised Case Study
An anonymized example from practice shows how a mezzanine tranche made a Berlin residential construction project possible, which threatened to fail due to the equity ratio. All information is changed to preserve confidentiality and serves only as an illustration – it does not represent a commitment or a return forecast.
A Berlin residential project with an equity gap
An experienced developer planned a residential project in a sought-after central Berlin district with total costs of approximately €14 million. The existing bank approved a senior loan covering 68% of costs, or around €9.5 million. This left a gap of approximately €4.5 million that would otherwise have required equity.
The problem: The developer’s own funds were largely tied up in two ongoing parallel projects. He would have had to postpone the Berlin project or prematurely reject a parallel project – both at noticeable costs. What was wanted was a structure that reduces the use of own funds without giving up company shares.
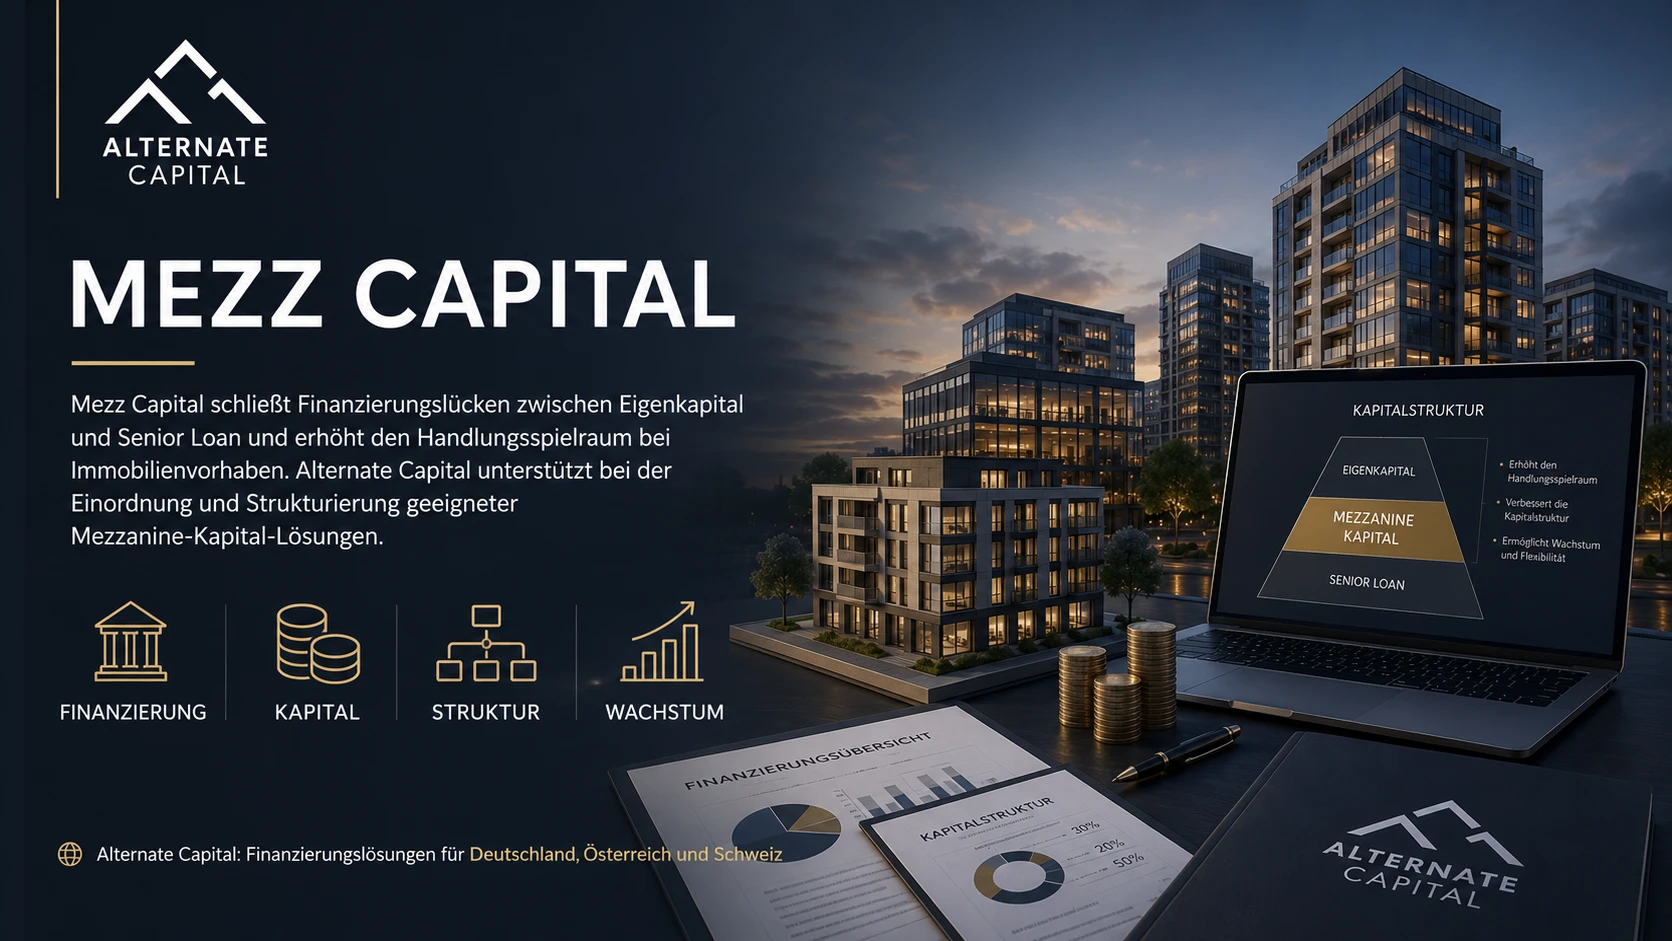
The solution: a second-rank mezzanine tranche
| Location | Without mezzanine | With mezzanine |
|---|---|---|
| Total costs | €14.0 million | €14.0 million |
| Senior bank loan | €9.5 million | €9.5 million |
| Mezzanine tranche | – | €3.2 million |
| Real own funds | €4.5 million | €1.3 million |
Through our lenders network, a mezzanine tranche of 3.2 million euros was structured, subordinated to the senior loan and secured via a subordinate land charge as well as a share pledging. As a result, the use of own funds fell from 4.5 to 1.3 million euros – the developer was able to start the Berlin project without touching a parallel project.
The subordination tranche was finalized, with repayment from the sale of the apartments. Part of the interest was capitalised until the end of the term in order to protect liquidity during the construction phase. The address of suitable lenders, the preparation of the documents and the coordination of the subordination with the bank took over Alternate Capital.
Project realized, equity spared
The project was executed as planned and sold off; the mezzanine tranche flowed back from the sales proceeds. Because the same project profit met significantly less used equity, the return on equity increased noticeably – despite the higher costs of the subordinated tranche. Decisive was the conservative calculation with buffers for construction time and sales.
The example is exemplary for the typical use of mezzanine capital: It does not replace a missing substance, but leverages a viable project. How the leverage pays off shows our Mezzanine Computational Example for property developers; bandwidths of costs explains the page to the Mezzanine interest rates.
Please note: All numbers and locations are anonymized and exemplary. Each financing depends on the individual case; no fixed terms, commitments or returns are guaranteed.
Is your project facing a similar equity gap?
Submit the key data – we check whether and to what extent a mezzanine tranche is realistic for your project.

Jürgen Kronawitter
Jürgen Kronawitter specialises in structured real estate finance. He helps property investors, developers and portfolio owners implement complex financing solutions. His work focuses on structuring and arranging senior loans, whole loans, mezzanine capital and bridge loans, as well as tailored financing for acquisitions, investment properties, developments and refinancing. By combining conventional bank lending with alternative capital sources, he develops financing structures for domestic and international property projects.
Jürgen Kronawitter on LinkedIn → More about the author