A higher debt contribution
Where equity is committed to several projects, a whole loan can provide leverage above conventional bank levels without a separate mezzanine negotiation.

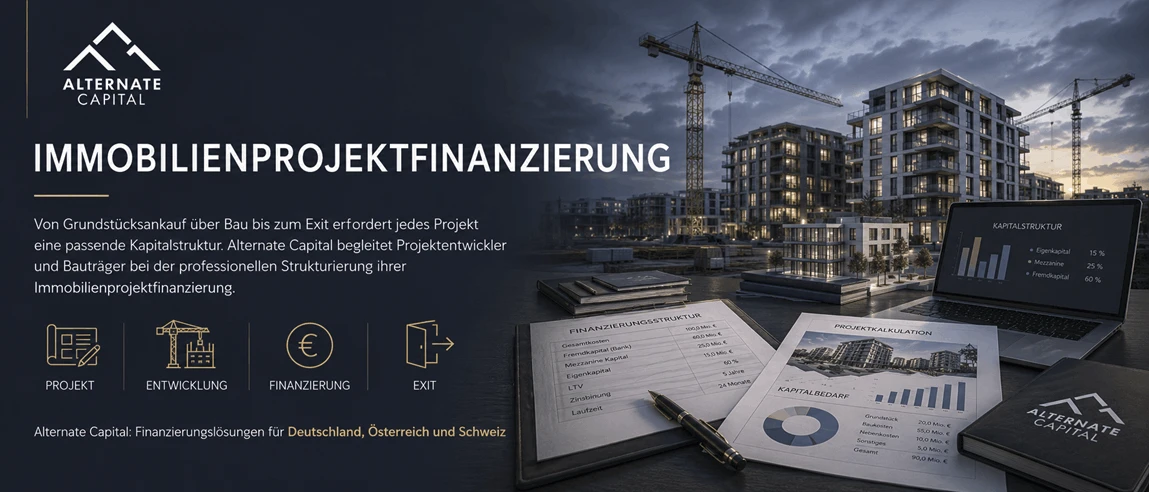
A whole loan combines senior and subordinated debt within a single financing: one lender, one agreement and one assessment. Alternate Capital structures whole loans for property projects from €750,000 to €180 million in Germany, Austria and Switzerland.
A property project’s capital structure traditionally has several layers: a first-ranking Senior loans from a bank, complemented by Mezzanine capital to address the equity gap. Two lenders also mean two assessments, two agreements, subordination arrangements and additional coordination throughout the term.
The Whole loans addresses this issue. A single lender, usually a debt fund or institution, provides the entire debt facility, typically up to approximately 85–90% of total costs. The blended rate lies between bank lending and subordinated debt pricing, while avoiding separate intercreditor negotiations and parallel approval processes.
Whole loans have become an established option where banks lend more cautiously. They replace separate senior and subordinated tranches with an integrated structure and a single point of contact.
A whole loan does not replace every bank loan, but can provide an efficient structure in particular circumstances.
Where equity is committed to several projects, a whole loan can provide leverage above conventional bank levels without a separate mezzanine negotiation.
One assessment rather than two: where construction costs and MaBV deadlines continue to run, the speed of the lending decision can matter more than a small difference in the interest margin.
Buyers with a credible financing commitment negotiate from a stronger position. A whole loan can provide sellers with greater certainty of completion.
Refurbishment, re-letting and exit: where conventional banks are reluctant to accept transitional risk, a whole loan may fund the period before stabilised occupancy.
The integrated structure can accommodate repayment from individual unit sales, including proceeds held in a notarial client account.
For core properties with stable rent and a long investment horizon, a conventional Senior loans is usually the lower-cost choice.
The trade-off: The blended rate exceeds pure bank lending rates. Lenders also expect reliable documents, a credible exit and experienced sponsors. A whole loan is a financing option rather than a discount.
Total costs, equity, timetable and exit: we establish a realistic leverage level and term.
We prepare property particulars, cost appraisals, sensitivity analyses and the security proposal for lender assessment.
We approach debt funds and institutional lenders whose criteria fit the project and financing amount.
We compare terms, negotiate and coordinate due diligence through to drawdown and beyond.
Key whole loan questions explained through our financing practice, in audio and video.
Why whole loans are in demand, realistic leverage levels and the factors lenders assess.
Original recording in German.
Another episode: “Whole loans in the property market” in the podcast hub
Original recording in German.
Both approaches cover the same economic funding requirement. A whole loan comes from one lender under one agreement at a blended rate. A senior-plus-mezzanine structure involves two agreements, separate assessments and subordination arrangements between the lenders.
Indicative levels reach approximately 85–90% of total costs or 75–80% of value, depending on location, asset class, presales or pre-letting and sponsor experience. The specific amount follows the project assessment.
With complete documents, term sheets are often possible within two to four weeks. Depending on due diligence, drawdown typically takes six to ten weeks.
No. Interest, the term and leverage depend on the individual case. Reliable terms require a document review and lender feedback. A blanket promise of a rate would be inappropriate.
Loan-to-cost (LTC) measures the share of total project costs funded by the loan. A senior bank loan typically reaches 60–70% LTC, while a whole loan can reach approximately 85–90%. This materially affects project funding: on €10 million of costs, increasing LTC from 65% to 88% reduces the equity requirement by €2.3 million.
Maximum leverage depends on the asset class, location, presales or pre-letting, and sponsor experience. Residential projects may attract higher leverage than specialist assets, and established locations may support more than peripheral markets. An experienced sponsor with a sought-after project can generally target stronger terms than a first project in a less certain location.
The higher leverage has a cost: the blended rate exceeds a pure senior bank rate. The structure makes economic sense where the improvement in equity returns outweighs that premium, which is more likely for higher-margin projects. We compare a whole loan with separate senior and mezzanine finance for your project, so the decision is based on the financial appraisal.
Send total costs, available equity, location and timetable through our initial assessment form. We will assess whether a whole loan or a combined structure is more appropriate.

Jürgen Kronawitter specialises in structured real estate finance. He helps property investors, developers and portfolio owners implement complex financing solutions. His work focuses on structuring and arranging senior loans, whole loans, mezzanine capital and bridge loans, as well as tailored financing for acquisitions, investment properties, developments and refinancing. By combining conventional bank lending with alternative capital sources, he develops financing structures for domestic and international property projects.
Jürgen Kronawitter on LinkedIn → More about the author