Increase at the existing bank
Cheapest condition, but depending on the willingness and speed of the institute – and often associated with reconditioning of the overall commitment.

Between the present value of your property and the remaining debt lies capital that does not work. If you want to borrow your property, you will find the practical instructions here: three ways, a sample calculation, the typical mistakes – and the question of when the step is really worthwhile. The service page with all variants: additional borrowing Property.
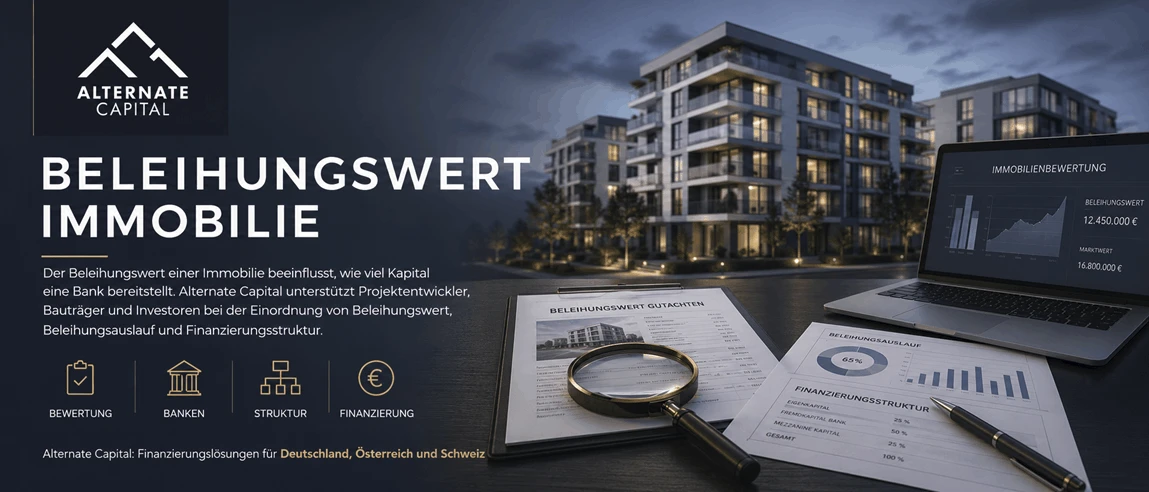
The principle in numbers – a rented apartment building, bought twelve years ago:
| Location | Value |
|---|---|
| Purchase price at that time | €3.2 million |
| Market value today | €5.4 million |
| Outstanding loan | €1.7 million |
| New release (68 % LTV) | €3.67 million |
| Freeing of liquidity | approx. €1.97 million |
Simplified example without costs/taxes; accepted expiration and debt servicing capacity decide in individual cases. No financing commitment.
Two drivers create this reserve: Increase in value (market, rental development, modernization) and Eradication. Both work silently for years – until they are activated. Basics for valuation are provided by the glossary entry Mortgage lending value.
Market value indication, residual debt, land register, rental income – the factual basis.
Realistic Expiration × Value − Residual Debt = Potential; debt service against rental check.
Increase, subordination or refinancing – according to costs, speed and contractual situation of the existing bank.
Address in parallel, compare conditions and incidental costs – do not take the first offer.
Rating, contracts, land register – payout typical in four to twelve weeks depending on the way.
Keep the intended use available: Acquisition, Capex or Project equity – a clear purpose noticeably improves condition and test speed.
Cheapest condition, but depending on the willingness and speed of the institute – and often associated with reconditioning of the overall commitment.
Second lenders behind the bank: fast, discreet, without intervention in the favorable investment property finance – at close conditions Mezzanine pricing.
New total loan with a higher leverage – economically often the best solution at the end of the fixed interest rate; the timetable is under Refinancing.
The practical sequence: ways, prerequisites and real case constellations from the structuring.
Original recording in German.
All episodes in the Podcast hub
Original recording in German.
In the case of the increase, it decides itself; in the case of subordination in the second place, its approval is generally not necessary – we check notification obligations from the loan agreement in advance.
Our focus is on rented properties and professional projects from €750,000 – where the rental cash flow carries the debt service. We do not depict pure home loans for consumer purposes.
The borrowing itself does not; the deductibility of the interest depends on the purpose – your tax consultant clarifies this, we provide the financing structure.
Subordination in second place: often three to six weeks. Increase and refinancing: depending on the institution, six to twelve weeks from complete documents.
Anyone who wants to borrow a property for the first time often underestimates how plannable the process can be – provided that it is set up cleanly from the beginning. In practice, additional borrowing follows a clear sequence that extends over a few weeks and in which the preparation decides on the speed.
At the beginning is the valuation. The current market value of the property – ideally proven by current comparative values or a short report – determines how much mortgage reserve there is at all. At the same time, the existing burden is clarified: How high is the remaining debt, which land charge are registered, are there prepayment clauses? The difference between accepted loan-to-value ratio and residual debt results in the freed-up capital. Only when these numbers are on the table is it worth talking to lenders.
In the next step, the path is decided: increase at the existing bank, a subordinated loan in the second rank or a complete rescheduling with a higher leverage. Each route has its own costs and speeds – the second rank is often the fastest, because the cheap investment property finance remains untouched. After selection of the path, valuation by the lenders, credit decision, if applicable, land debt order with the notary and finally the payment. With good preparation, there are often only four to eight weeks between initial talk and liquidity. We take over the value indication, addressing several lenders and coordinating until the payout – so you can take care of the use of the capital, not the paperwork.
A practical tip: a well-prepared indication of value helps the whole process move more efficiently. Current comparable rents, meaningful property documentation and a clear land register extract reduce lender questions and avoidable delays before drawdown. We handle this preparation with you.
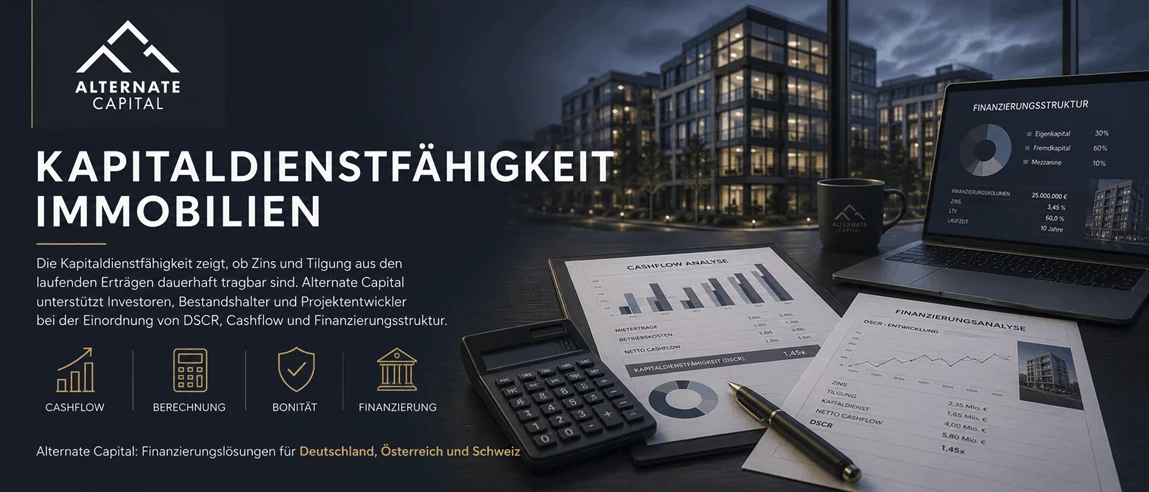
Property value, residual debt, rental income – three details are sufficient, and we quantify your realistic mortgage reserve along with the appropriate path.

Jürgen Kronawitter specialises in structured real estate finance. He helps property investors, developers and portfolio owners implement complex financing solutions. His work focuses on structuring and arranging senior loans, whole loans, mezzanine capital and bridge loans, as well as tailored financing for acquisitions, investment properties, developments and refinancing. By combining conventional bank lending with alternative capital sources, he develops financing structures for domestic and international property projects.
Jürgen Kronawitter on LinkedIn → More about the author