
Subordinated and Profit-Participating Loans
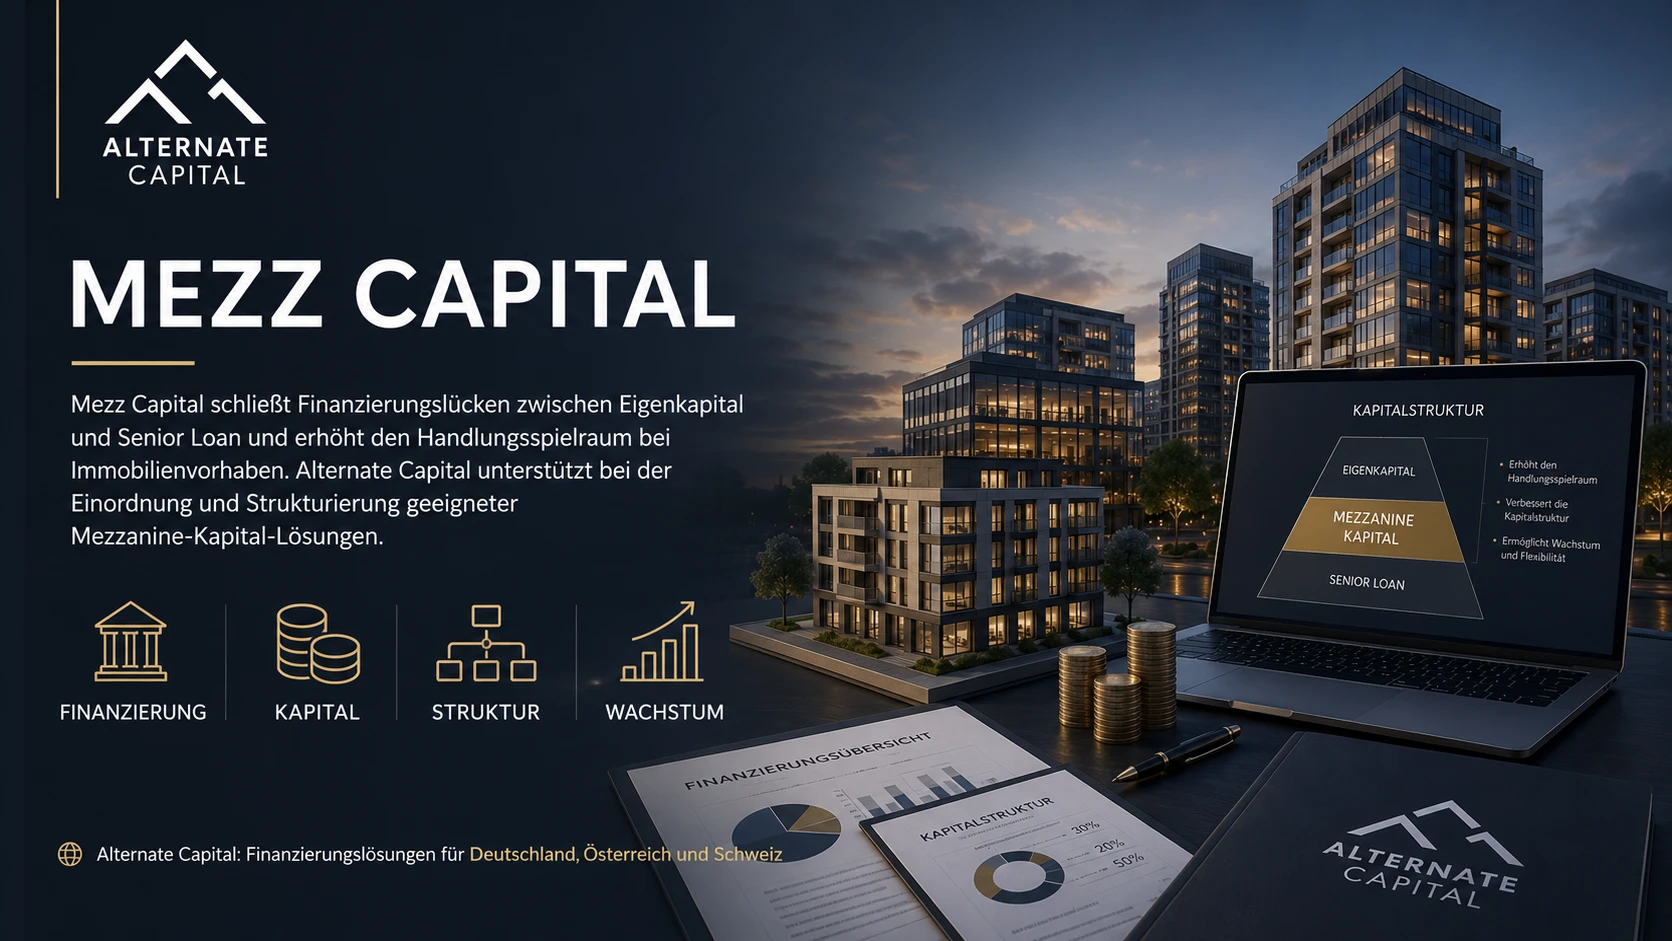
Subordinated loan and profit-participating loan are two closely related mezzanine forms. This guide explains the difference – subordination here, profit sharing there – and shows which structure fits for your real estate project.
The subordinated loan
A subordinated loan withdraws with its repayment claim behind the first rank creditors – usually via a qualified subordination, which links interest and repayment to the ability to pay. It is the classic mezzanine form: fixed interest, fixed term, no profit sharing and no shareholder rights. For the bank, it acts as an additional equity.
Details and pricing structure explains the service page Subordinated loans.
The profit-participating loan
In the case of profit-participating loan, the fixed interest is replaced by (or in addition to) a profit or earnings share of the lenders. He participates in the success of the project, but – unlike a silent partner – is not involved in the loss and receives no shareholder rights. Legally, it remains a loan.
The advantage for the project sponsors: lower current interest burden in the capital-intensive construction phase, because part of the remuneration flows only from the success of the project. More about this on the glossary page Profit-participating loans.
- Subordinated loans: fixed interest rate, calculable, no participation in success.
- profit-participating loan: Lower base rate plus profit sharing.
- Together: Subordination, no voting rights, pure loan nature.
- Election: depends on margin profile, construction phase and risk sharing.
What form for which project?
The subordinated loan fits if planning is in the foreground and the current interest burden is sustainable. The profit-participating loan is worthwhile for high-margin projects, whose liquidity should be spared in the construction phase and in which the lender can participate in the success. In practice, both forms are designed project-specifically – we structure the variant that fits the bank contract, balance sheet targets and exit.
Tax and accounting aspects
The choice between subordinate and profit-participating loan also has fiscal and accounting dimensions. Interest payments on a subordinated loan are generally deductible as operating expenses at operational instigation – whereby the interest rate barrier must be observed. In the case of profit-participating loan, the profit share can be treated differently for tax purposes depending on the design. On the balance sheet, both forms of subordination have a similar effect to equity without being genuine equity – an advantage for key figures such as the equity ratio.
Because these effects are complex and dependent on individual cases, the concrete design belongs in the hands of tax consultants and financing structurers. We provide the financing side, the tax assessment is accompanied.
Combination of both forms in practice
In practice, the two forms are not mutually exclusive – they are often combined. A basic model with a fixed base interest rate ensures predictability, an additional profit component (equity kicker) contributes the lenders to success and at the same time reduces the current interest burden. This creates a structure that protects liquidity in the critical construction phase and allows the lenders to participate fairly in the results. Which mix is optimal depends on the project margin, construction phase and risk sharing – and is negotiated individually.
Quick answers
What distinguishes subordinate and profit-participating loan?
The subordinated loan has a fixed interest rate with no participation in the success. The profit-participating loan shares the lenders in the profit, often against a lower basic interest rate.
Will the lenders participate in the loss?
No, not in both forms. Unlike the silent partner, the lender does not bear any loss participation; it remains a legal loan.
Which form is more favorable?
This depends on the course of the project: The profit-participating loan can become more expensive if successful, but protects the ongoing liquidity. The subordinated loan is more plannable.
Finance your property plans
Send us the key details. We will assess the appropriate financing structure and usually respond within 1–2 working days.

Jürgen Kronawitter
Jürgen Kronawitter specialises in structured real estate finance. He helps property investors, developers and portfolio owners implement complex financing solutions. His work focuses on structuring and arranging senior loans, whole loans, mezzanine capital and bridge loans, as well as tailored financing for acquisitions, investment properties, developments and refinancing. By combining conventional bank lending with alternative capital sources, he develops financing structures for domestic and international property projects.
Jürgen Kronawitter on LinkedIn → More about the author