Equity gap in new construction
The bank stands, the own funds are in other projects: The subordinate tranche closes the gap and keeps the pipeline running.

mezzanine capital is the slightly different form of financing for real estate: no bank loans, no equity – but the layer in between, which makes projects possible if both are not enough. This page explains how companies receive mezzanine capital for real estate finance, what it is used for and what requirements apply.
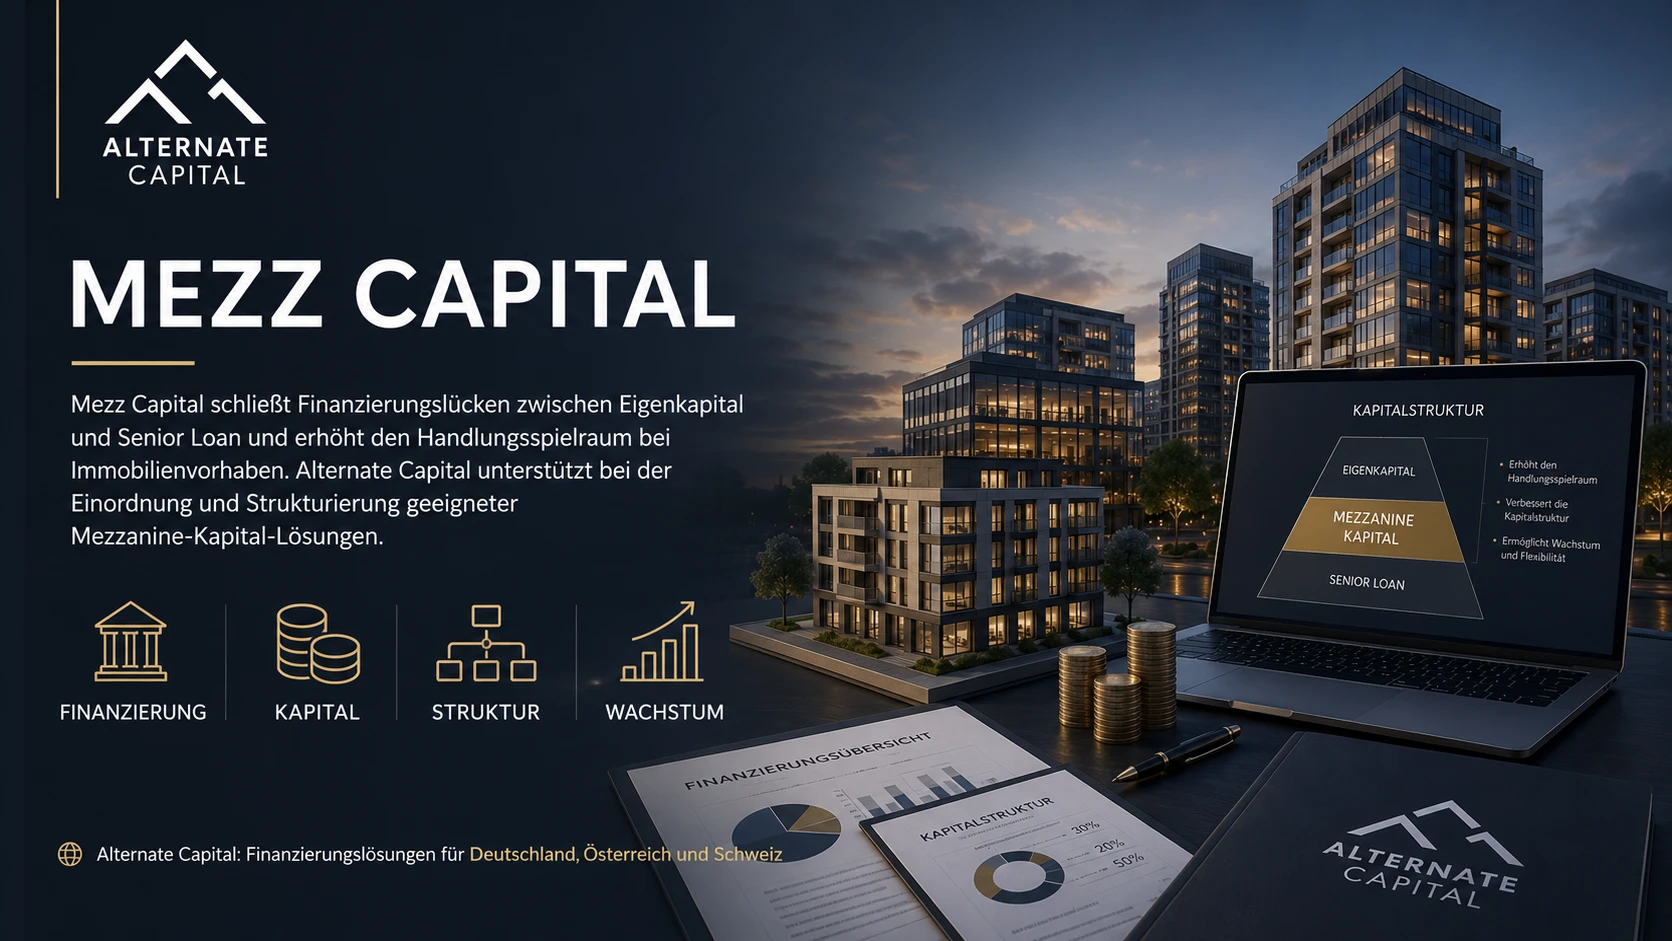
The term comes from the Italian “mezzanino”, the mezzanine – and that’s where mezzanine capital sits: between first-rank bank loan and equity. Mostly legally as Subordinated loans Designed with qualified subordination, it looks like equity economically: it improves the lending structure and often makes bank financing possible in the first place.
This form of financing is “different” in three points: it comes Not from banks, but by debt funds, family offices and institutional investors. It shall: Not tested according to Scheme F, but project-specific – substance and exit count more than balance sheet figures. And it will cost you more than bank capital, because the lenders carries subordinate risk – but pays off via the equity lever, as the calculation example under Mezzanine finance for developers shows.
Typical size: Bank 65–75 % of costs, mezzanine capital 10–25 %, real own funds 5–15 %.
The bank stands, the own funds are in other projects: The subordinate tranche closes the gap and keeps the pipeline running.
mezzanine capital carries the phase that banks avoid – until approval and project financing stand.
More projects in parallel with the same equity – the standard lever of the Property development finance.
Second-rank subordination activates Lending Reserve for new investments – which Additional borrowing.
Combined with Bridge finance or Whole loans This creates transaction security in the bidding process.
Share acquisitions, hereditary disputes, restructuring – wherever capital close to equity is quickly lacking.
The path leads to Targeted approach instead of bank desksMezzanine lenders – debt funds, family offices, insurers – have defined lending criterias by region, asset class, phase and ticket size. Those who request outside the profile are not checked; those who request with incomplete documents burn addresses.
Successful requests combine three things: Fitting (the right five lenders instead of fifty wrong ones), Proposal for a committee (exposé, figures, sensitivities, concept of collateral) and Parallel Address for real conditioning competition. It is precisely this craft that Alternate Capital takes over – with a network that has grown over the years and the experience of how investment committees decide. The lenders landscape in detail: Mezzanine lenders.
Amount, maturity, collateralisation, interaction with the bank.
Exposé, figures, sensitivities – capable of committeeing.
Shortlist, parallel address, term-sheet comparison.
Subordination, contracts, payment – and support beyond.
Market-standard high single-digit to medium-double-digit percentage range per year – depending on phase, leverage, collateralisation and sponsor. Bandwidths and calculation examples: Mezzanine interest rates.
From about €750,000 subordination requirements per project, up to double-digit million amounts – Germany, Austria and Switzerland-wide.
For complete documents: initial feedback in one to two weeks, payout typically in four to eight weeks.
No – both spellings mean the same instrument; “mezzanine capital” is the Germanized summary. The main page on the topic: Mezzanine property finance.
mezzanine capital for real estate finance is a powerful instrument – but not a panacea. Its strength lies in strengthening the equity base and enabling larger or more projects in parallel without surrendering company shares. This leverage makes it the preferred tool of growth-oriented property developers and property developers, which lack the own funds for the next project.
The limitations are equally important. Mezzanine capital cannot compensate for a poor project or a complete lack of own funds. Lenders examine the project, track record and exit carefully. Leverage works in both directions: in weak projects, it can amplify losses as well as gains. Understanding these limits is essential to using it appropriately.
The correct use of mezzanine capital for real estate finance therefore begins with an honest classification: Does the project bear the additional costs? Is the exit resilient? Are own resources sufficient as a basis? We clarify these questions in the initial estimate – and also cancel if subordinated capital is the wrong tool for a project.
mezzanine capital for real estate finance is a powerful but not a universal instrument. Properly used, it strengthens the equity base and enables growth without a share levy; incorrectly used, it makes weak projects more expensive without making them sustainable.
The key lies in the honest classification at the beginning: Does the project bear the additional costs, is the exit resilient, are the own funds sufficient as a basis? We clarify these questions – and use mezzanine capital for real estate finance only where it really forms the right building block.
Submit your project, own funds and exit – we will honestly tell you whether and under what conditions mezzanine capital can be presented for your real estate finance.

Jürgen Kronawitter specialises in structured real estate finance. He helps property investors, developers and portfolio owners implement complex financing solutions. His work focuses on structuring and arranging senior loans, whole loans, mezzanine capital and bridge loans, as well as tailored financing for acquisitions, investment properties, developments and refinancing. By combining conventional bank lending with alternative capital sources, he develops financing structures for domestic and international property projects.
Jürgen Kronawitter on LinkedIn → More about the author