
Short-Term Bridge Finance for Real Estate
Bridge financing bridges short-term capital requirements for real estate – up to sale, bank payment or refinancing. This guide explains usage cases, procedure and the delineation to the Bridge Loan and the classic bridge finance.
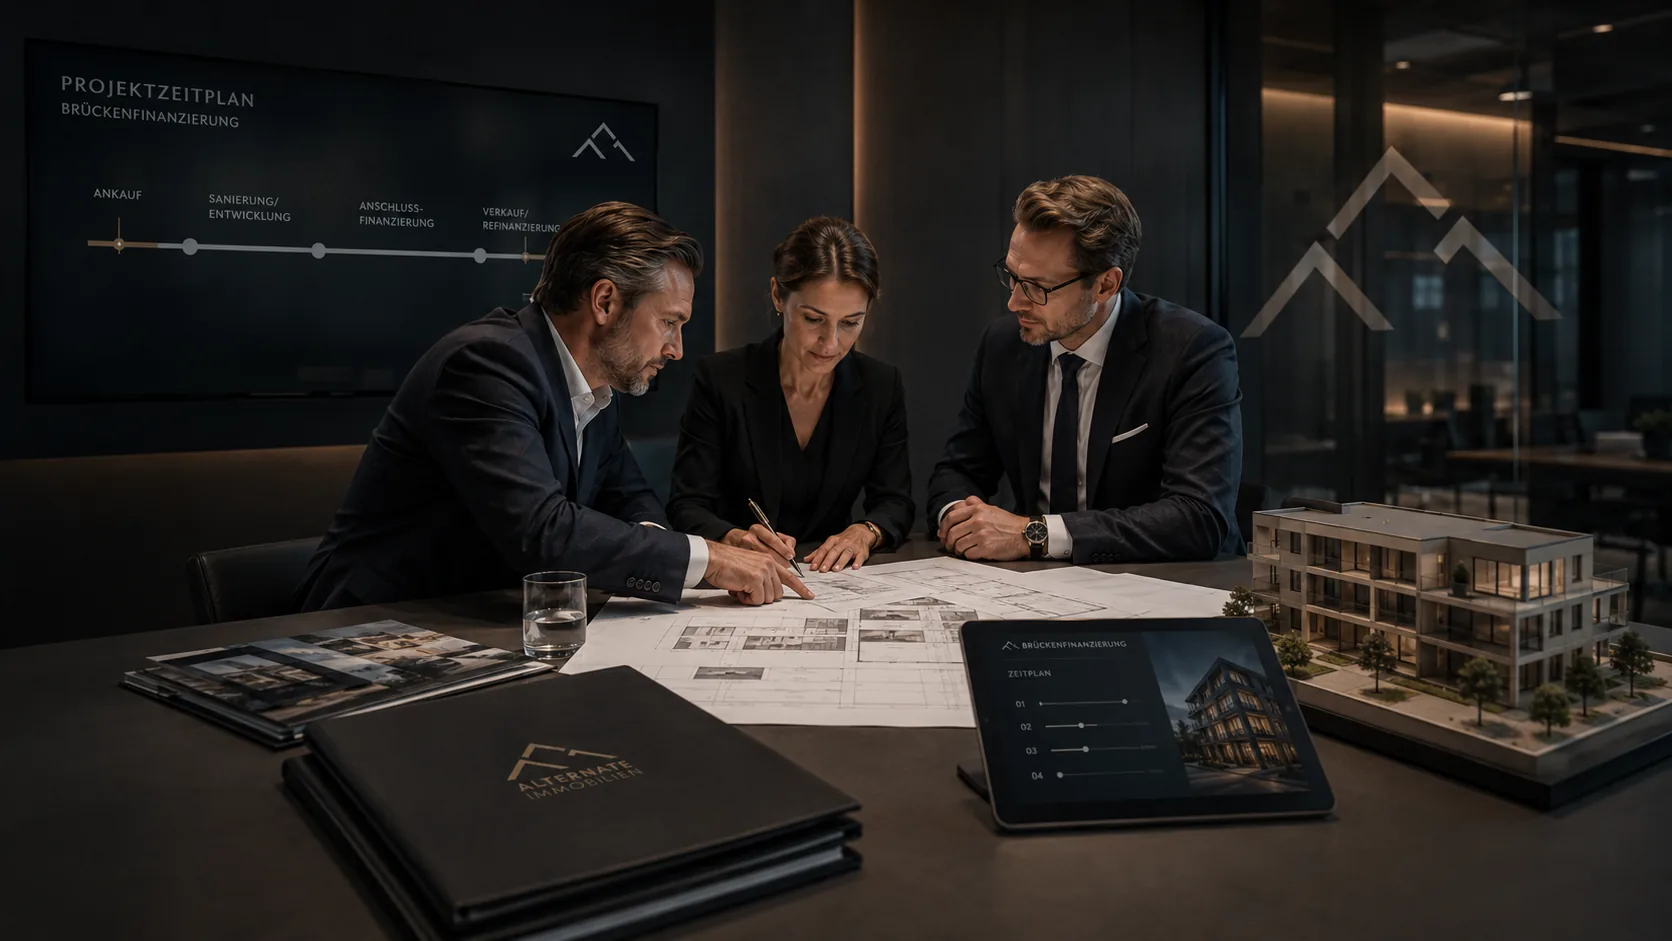
What Bridge Financing Does
Bridge financing – literally “bridge financing” – is a short-term, usually first-ranking secured real estate loan. It is designed for speed: short duration (typically 6–24 months), bullet structure and return from a clearly defined event. Above all, lenders examine property value, loan-to-value ratio and the security of the exit – not long-term cash flow histories.
In terms of content, the bridge financing is congruent with the Bridge loan and the German Bridge finance – they are different names of the same tool.
Typical use cases
Always useful if time is the critical factor and a reliable repayment path is fixed:
- Purchase under time pressure in the tendering procedure or in the case of a short notary’s appointment.
- Interim funding until the payment of a promised bank financing.
- Land security before building rights.
- Releasing capital before a planned sale.
- Transition until long-term refinancing.
Duration and costs
The process is lean: initial estimate, documents (property, land register, purchase contract, own funds, exit), addressing suitable lenders, term sheet and payout – often in two to six weeks for complete documents. Due to speed and short duration, the interest rate is above the classic bank financing; however, the bridge financing is often favorable if it secures a buying opportunity or a schedule. The full cost and the exit logic explains the service page to bridge finance.
The importance of the loan-to-value ratio in bridge financing
Because bridge financing primarily focuses on the property value and the exit, the loan-to-value ratio (loan-to-value) is the central control variable. Normally, it moves between 60 and 75 percent of the property value – exceptions are possible in the case of very liquid positions and a strong exit. A conservative runout not only improves the condition, but also increases the speed of the promise, because the lender has more safety buffer. For the capital seeker, therefore, the following applies: Those who do not squeeze out the maximum, but leave buffers, often finance faster and cheaper.
In addition, the value of the security in the enforcement scenario is decisive. lenders do not evaluate the optimistic sales prospectus, but the realistically achievable value – a point at which serious providers differ from dubious providers.
When to pay the higher costs
Bridge financing is more expensive than classic bank financing – that’s the price of speed and flexibility. Whether this pays off shows the overall consideration: An earlier bid in the bidding process, a better purchase price through quick ability to act or the avoidance of a contractual penalty can offset the higher interest costs many times over. On the short term, the absolute interest expense is often manageable. We prepare this invoice transparently before each conclusion – including a stress test in case the exit comes later than planned.
Quick answers
What Is the Difference Between Bridge Financing and Bridge Loan?
None of relevance – “Bridge Financing”, “Bridge Loan” and “bridge finance” refer to the same short-term, exit-oriented real estate finance.
How fast is bridge financing available?
With complete documents, promises are often possible in one to three weeks, the payout in two to six weeks.
What happens if the exit is delayed?
Good contracts include renewal options for a fee; interest reserves are planned so that a delay does not become an emergency.
Finance your property plans
Send us the key details. We will assess the appropriate financing structure and usually respond within 1–2 working days.

Jürgen Kronawitter
Jürgen Kronawitter specialises in structured real estate finance. He helps property investors, developers and portfolio owners implement complex financing solutions. His work focuses on structuring and arranging senior loans, whole loans, mezzanine capital and bridge loans, as well as tailored financing for acquisitions, investment properties, developments and refinancing. By combining conventional bank lending with alternative capital sources, he develops financing structures for domestic and international property projects.
Jürgen Kronawitter on LinkedIn → More about the author