
Financing Property Projects with Mezzanine Capital
mezzanine capital is the key to real estate projects despite limited own funds. This guide shows how subordinated capital finances project developments, development projects and divisions – with operational cases, structure and process.
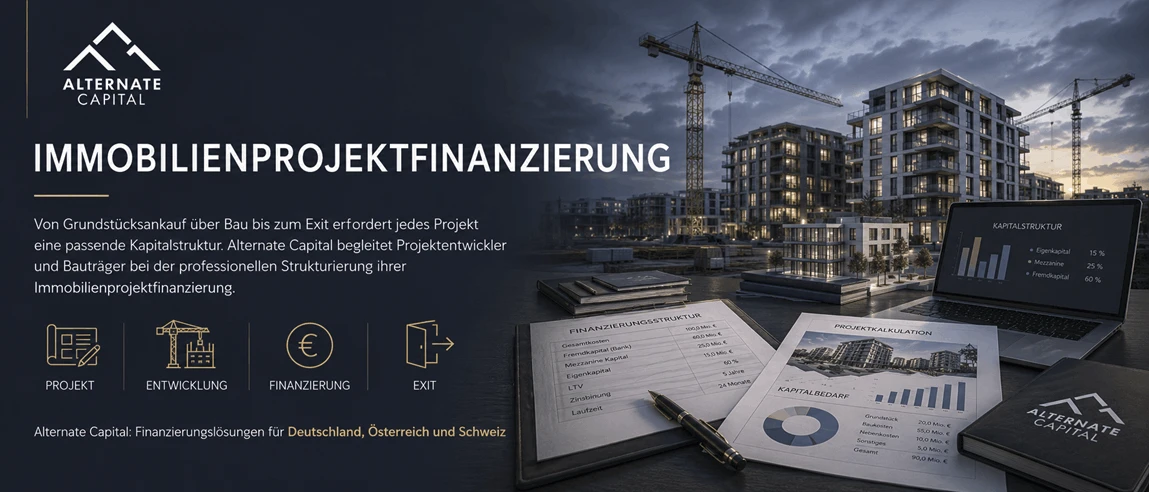
Why Real Estate Projects Use mezzanine capital
Project developments are capital-intensive and tie up a lot of money for months before revenues flow. Since the banks have lowered their leverage, there is a gap between Senior Loan and equity that fills pure equity only difficult and expensive. mezzanine capital closes it – and acts as an additional equity for the bank.
The effect: projects are feasible with fewer own resources, and released capital enables several projects in parallel. The calculated number example can be found on the page Mezzanine finance for developers.
Typical project constellations
mezzanine capital fits all phases of a project cycle:
- Purchase of land before building law, until the project financing takes effect.
- Equity gap in the new building next to the Senior Loan.
- Construction works on the conservation of own resources and the extension of the pipeline.
- Breakdowns: Purchase, refurbishment, retail sale – combined with Condominium conversion finance.
- Transition phases until sale or refinancing.
Structure and operation
Typical is the stratification Bank 60–75 %, Mezzanine 10–25 %, Own funds 5–15 %. Alternatively, a Whole loans both layers of debt at a lender. The process: initial estimation, structural definition, committee-capable documents, targeted investor approach, negotiation and closing. Decisive for the commitment are substance, real own funds and a resilient exit – without this basis, there is no serious subordinated capital.
From the idea to structured project financing
At the beginning of every financed real estate project is an honest inventory: What is the total cost, how much equity is available, what is the schedule and – the most important question – how is it returned? The capital structure is derived from these key data. If the bank leverage is not enough, mezzanine capital closes the gap; if speed is crucial, a Whole Loan may be the better choice. This structure is not decided at the green table, but developed from the specific project.
Only when the structure is in place, the preparation follows: Exposé, figures, sensitivity analyses and collateral concept must be prepared in such a way that a credit committee can make efficient decisions. This preparatory work is the difference between a request that is being reviewed and one that remains in the stack.
Risk management during the project
A project financed with mezzanine capital requires active risk management over the entire term. Increases in construction costs, delays in sales or postponed permits can jeopardize the original plan. Therefore, with serious structuring, buffers, interest reserves and extension options are planned from the outset. The leverage of the subordinated capital works in both directions – conservative calculation with stress scenarios is therefore not a freeze, but a duty. This is exactly what the lenders pay attention to when examining.
Quick answers
Which real estate projects are suitable for mezzanine capital?
Project developments, development projects, divisions and purchases of land with a sustainable exit and real own resources. Substance and calculation are crucial.
How much equity do I still need?
In reality, 5–15 % usually remains real own funds. Without equity, subordinated capital cannot be displayed.
How fast is the financing?
For complete documents, first feedbacks are common in one to two weeks, the payout in four to eight weeks.
Finance your property plans
Send us the key details. We will assess the appropriate financing structure and usually respond within 1–2 working days.

Jürgen Kronawitter
Jürgen Kronawitter specialises in structured real estate finance. He helps property investors, developers and portfolio owners implement complex financing solutions. His work focuses on structuring and arranging senior loans, whole loans, mezzanine capital and bridge loans, as well as tailored financing for acquisitions, investment properties, developments and refinancing. By combining conventional bank lending with alternative capital sources, he develops financing structures for domestic and international property projects.
Jürgen Kronawitter on LinkedIn → More about the author